In the past month, the supply of USDe has rebounded, the price of ENA tokens has surged, and the stock price of Treasury Company StablecoinX has reached an all-time high.
Written by: Zhou, ChainCatcher
On September 22, around 1 PM, the USDe briefly dropped below 1 US dollar in the Binance spot USDe/USDT trading pair, hitting a low of 0.9202 US dollars before returning to around 0.9996 US dollars within a few minutes. ENA fell over 7% during the day.
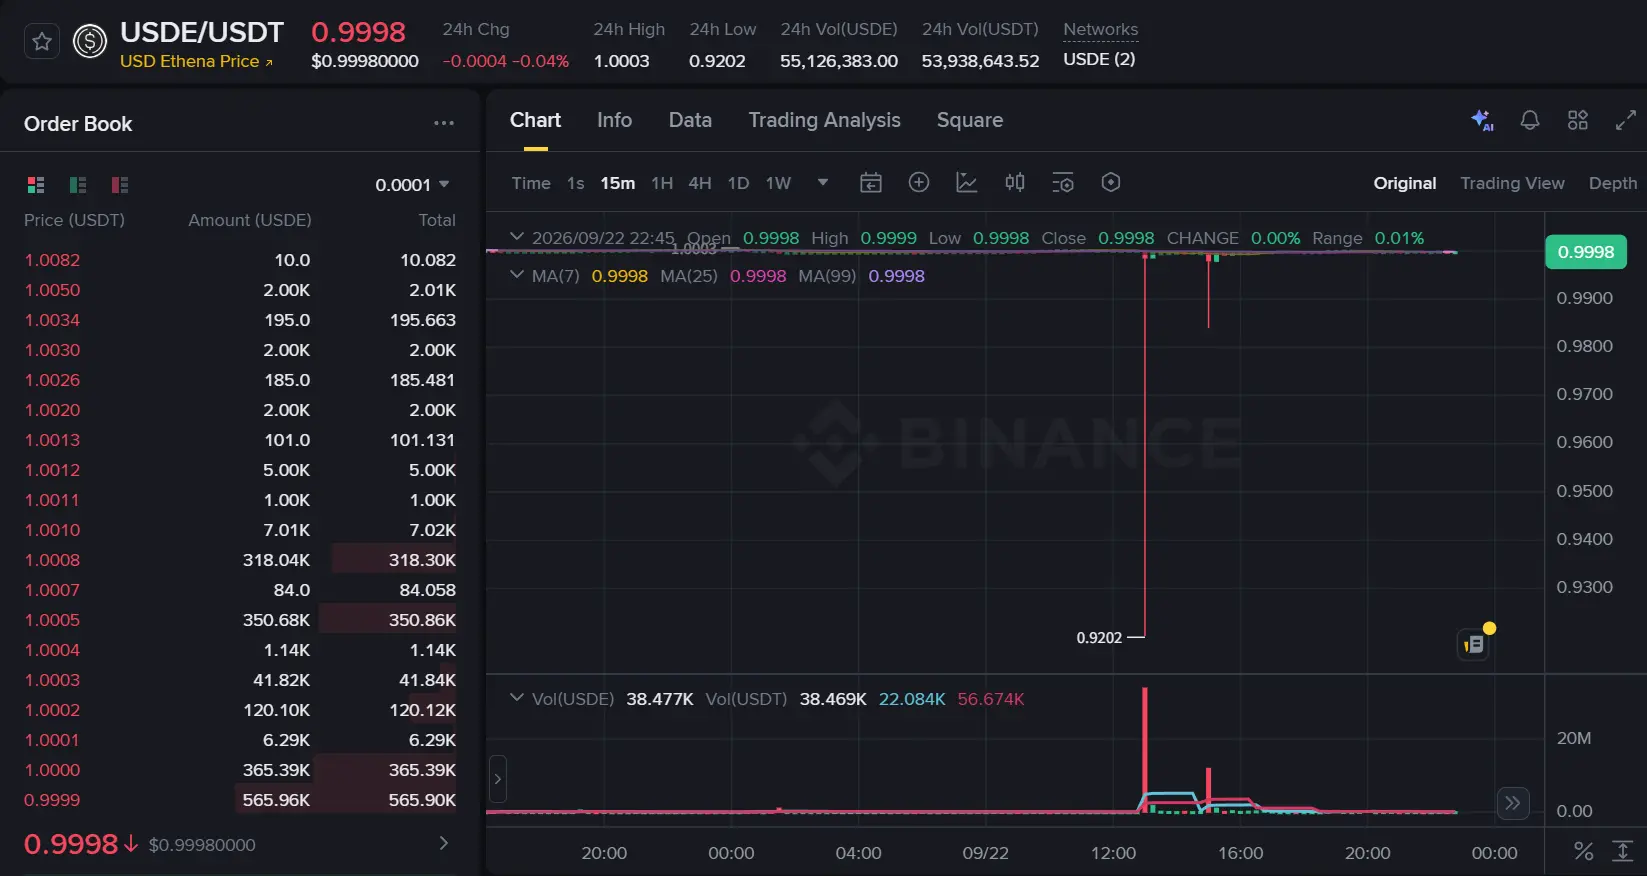
This fluctuation occurred before a planned wallet upgrade on Binance at 2 PM. During the upgrade, all deposits and withdrawals were paused for about an hour, and the overall maintenance window lasted until 5 PM, although spot and contract trading did not stop. However, there is currently no evidence to suggest that this decoupling was directly triggered by this maintenance.
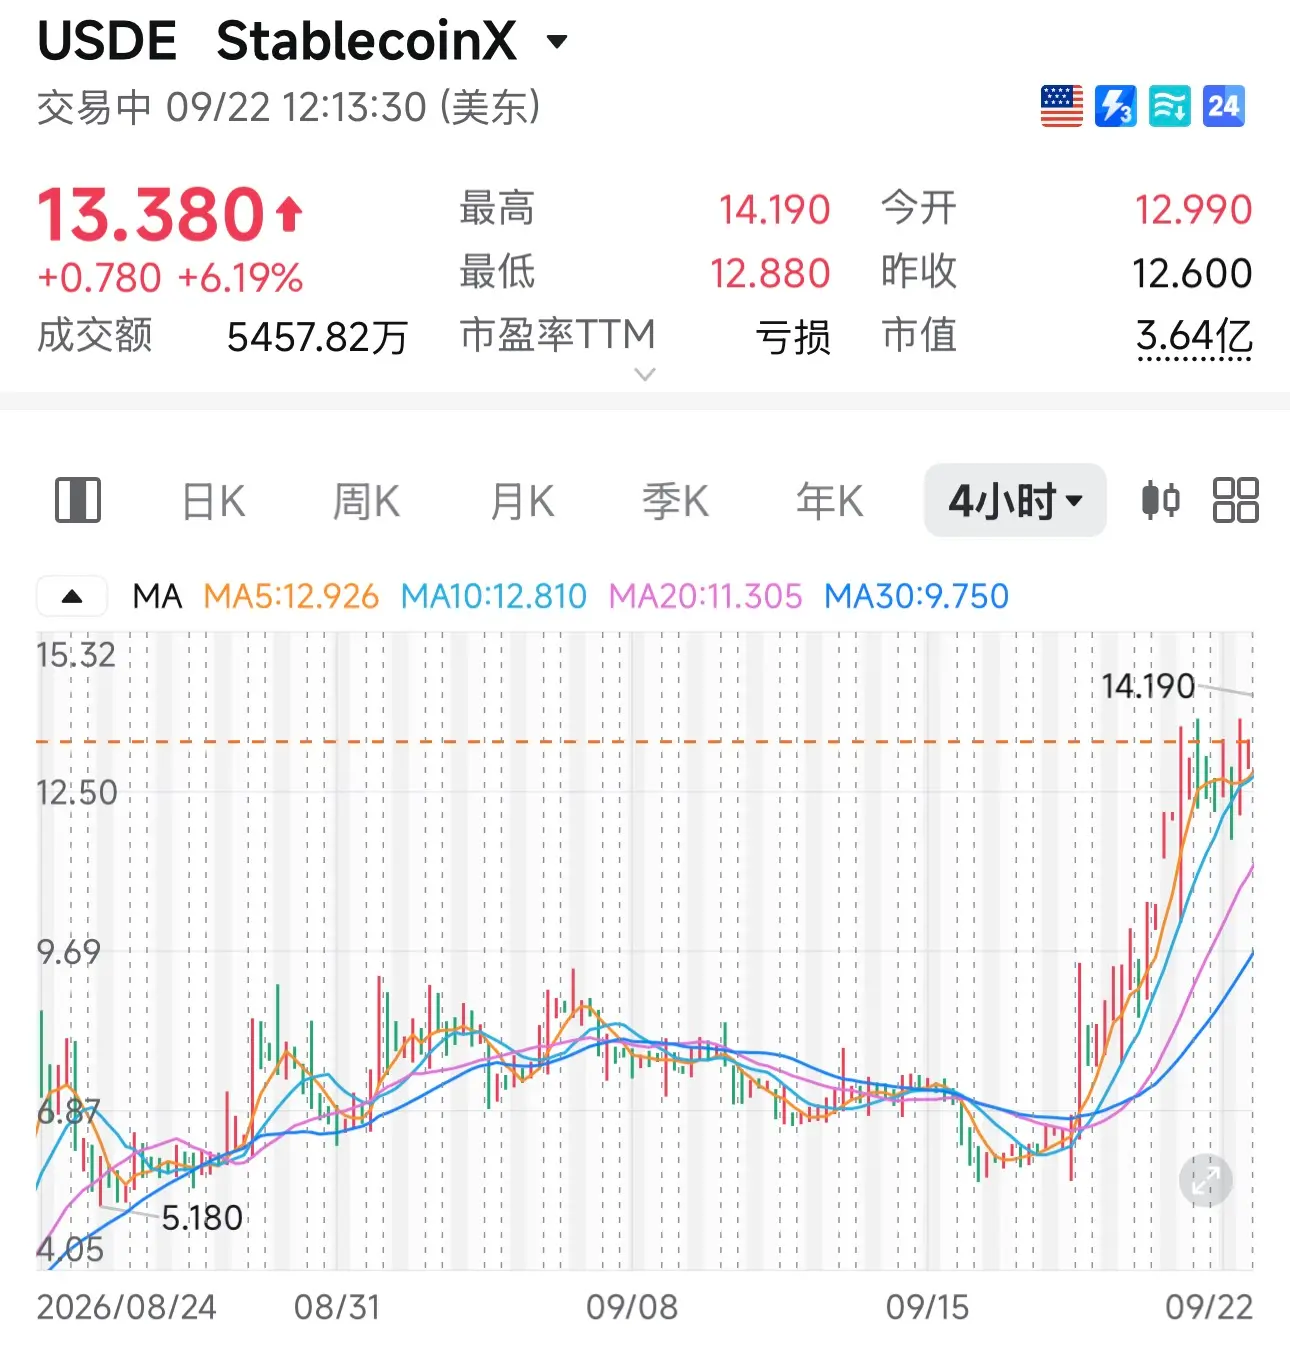
Last year, the supply of USDe at one point approached 15 billion US dollars, followed by months of blood loss. In the past month, it has recovered from about 4.1 billion US dollars to nearly 4.9 billion US dollars. During the same period, ENA increased by about 30%, and the stock price of Treasury Company StablecoinX, which holds related assets, rose from just over 5 US dollars to around 14 US dollars, setting a new historical high.
In this round of rebound, how much comes from market expectations of its token buyback system, how much stems from the actual recovery of the protocol's scale and revenue, and how much is simply an amplification of sentiment?
USDe lost blood for ten months and recoupled again
This is not the first time USDe has decoupled. During the collapse triggered by massive liquidation on October 11 last year, USDe briefly fell to 0.65 US dollars on Binance. In contrast, this time, the fluctuation to 0.92 US dollars seems more like a minor event, as the protocol's minting and redemption were not affected.
Crypto analyst Chen Mo wrote that the order book for USDe on centralized exchanges has always been thin, and it has also been used as collateral for opening contracts. The risk transmission of 1011 actually started from here. He mentioned that thereafter Binance included the actual redemption price of USDe in the price index, no longer just referring to the order book quotes, theoretically preventing a repeat of the chain liquidation seen on 1011.
Data shows that after 1011, the supply of USDe was halved from its peak and maintained at a low level for several months.
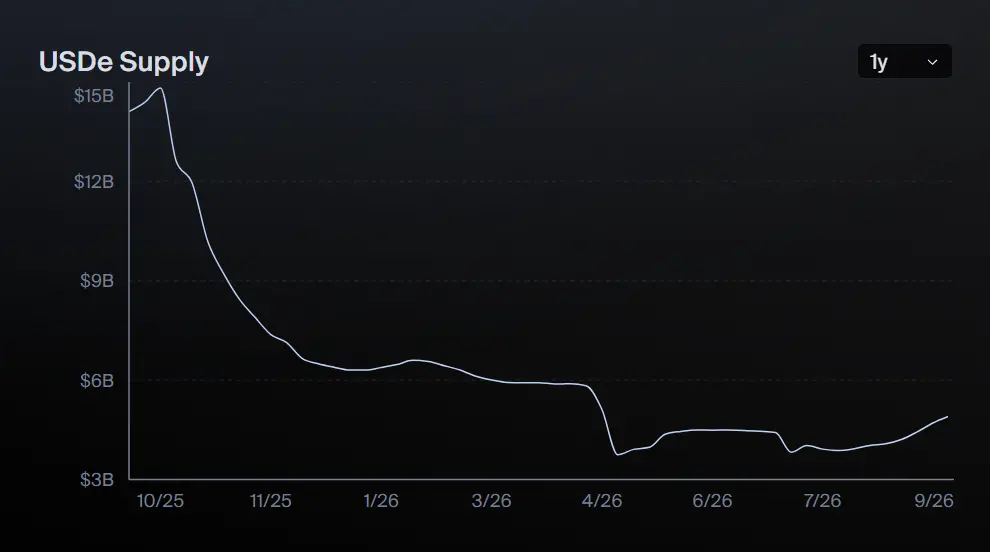
In April this year, the cross-chain bridge of the liquidity re-staking protocol Kelp DAO was attacked, resulting in a loss of about 292 million US dollars, accounting for about 18% of the circulating supply of rsETH. Ethena itself had no rsETH exposure, but due to the use of related cross-chain bridge technology, it prudently suspended its bridging services.
Platforms like Aave and SparkLend simultaneously froze the rsETH-related markets, causing panic to continue spreading along the liquidity re-staking chain, and USDe was swept up in it. From April 19 to 23, USDe was redeemed for about 1.68 billion US dollars, dropping to 3.9 billion US dollars at the end of the month, marking the second low point after 1011.
It is important to note that Ethena truly relies on the funding rates of hedging assets like BTC and ETH. Once these yields weaken, the interest rate spread between sUSDe’s exterior quotes and US treasury yields will be rapidly compressed.
During the redemption wave in April, the yield on sUSDe briefly dropped to around 3.5%, only slightly above US treasury yields, which was a direct reason for the accelerated withdrawal of funds at that time. The protocol managed to withstand this wave of concentrated redemptions with an instant buffer pool of over 90 million US dollars maintained in its redemption contracts, and the reserve fund was not utilized throughout.
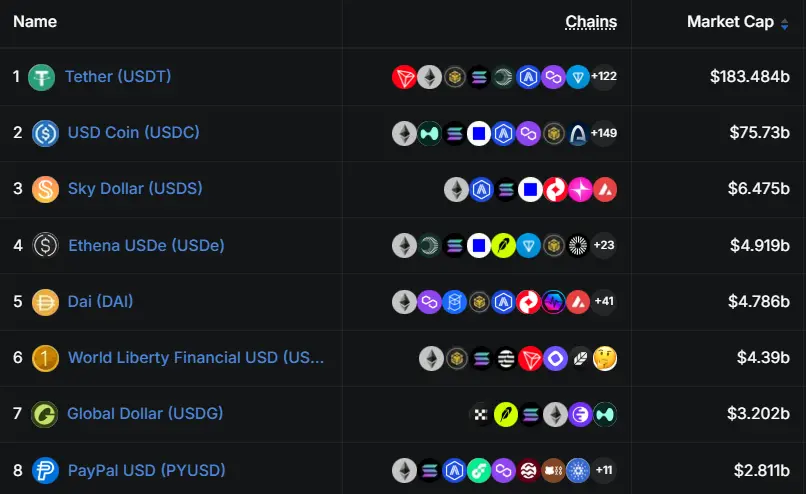
According to DefiLlama data, the current supply of USDe is about 4.9 billion US dollars, making it the fourth largest stablecoin in the entire network, only behind USDT, USDC, and Sky Dollar, and less than 200 million US dollars away from the fifth-ranked Dai.
Ethena token economics reform, buyback expectations fully charged?
At the end of August this year, the Ethena Foundation announced significant reforms to its token economics, proposing to use protocol revenue to buy back ENA. ENA holders are currently voting to decide on the "fee switch." When the supply of USDe reaches 7.5 billion US dollars, 95% of the net income from Ethena's brand business will be used for programmatic purchases of ENA, with the remaining 5% designated for growth.
This proposal was passed with high votes in the governance vote on September 2. The foundation also funded the repurchase of ENA shares previously unlocked and sold from some early investors, and categorized the protocol's intellectual property and value under the governance framework of ENA holders.
This reform also includes ending more than a year of monthly unlocks, with the originally monthly released investor shares set to be permanently released in one go on October 5.
This arrangement may instinctively lead people to feel that the end of the unlock is beneficial, but the actual situation is more complex. As early as the end of 2024, the protocol had set a version of thresholds, including a supply of USDe exceeding 6 billion US dollars, historical cumulative revenue exceeding 250 million US dollars, and access to four of the five major mainstream contract exchanges.
In September 2025, the supply of USDe briefly surged to 12 billion US dollars; these conditions were basically met, but the plan remained stuck at the risk committee approval and token holder voting stage, and had never officially launched. Shortly after, the 1011 event occurred, and the supply of USDe was halved, leading to the abandonment of this version of the plan.
The current supply of USDe is still 2.6 billion US dollars short of the target set by the reform. Based on the average recovery speed since the April low, there is a monthly growth of about 200 million US dollars, and it would take roughly 13 months to fill this gap. If calculated based on the accelerated pace observed in the past month, the time could be shortened to around 3 months.
It is worth mentioning that Treasury Company StablecoinX, which holds about 20% of the total supply of ENA, has performed better in stock price trends compared to other treasury companies, with its stock price rising from just over 5 US dollars to a high of 14.19 US dollars during trading on September 22 in the past week. Especially after the ENA lock-up waiver agreement reached with Ethena on September 17, the stock price has set new historical highs for three consecutive days.
From eating funding rates to a new bank that hasn't run smoothly yet
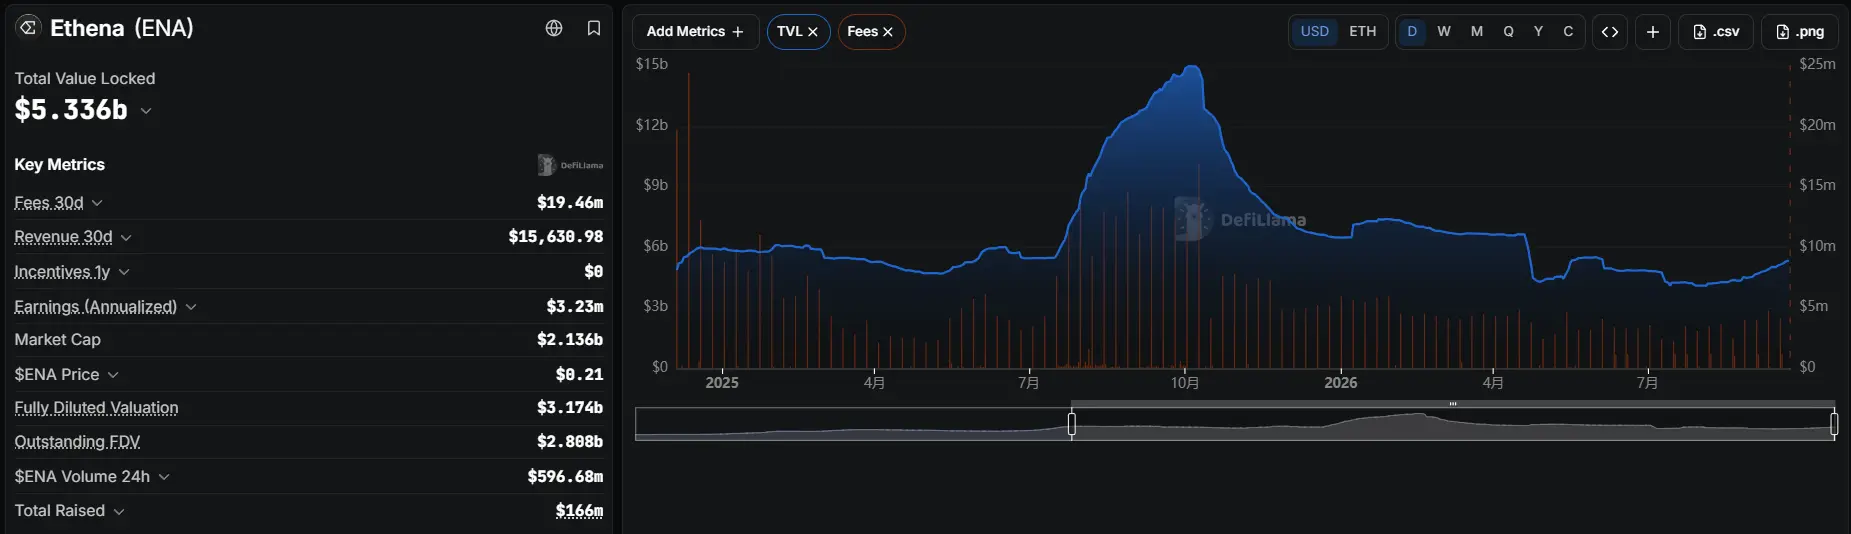
According to DefiLlama data, in the past 30 days, the total fees generated by the protocol have been about 19 million US dollars, but the revenue counted from the protocol side has only been a little over 10,000 US dollars. The fees include portions distributed to sUSDe holders, minting fees, and reserve fund shares, while the revenue only accounts for the minting fees and that small portion entering the reserve fund.
Currently, minting fees are basically exempted, and the reserve fund has not distributed shares for a long time, with almost all the revenue generated by the protocol being allocated to sUSDe holders and distribution channels, and not flowing to ENA token holders.
Since the low in April, for the first time, RWA, institutional lending, and DeFi lending have emerged in the system-backed assets' categories, which were previously absent.
A comparatively solid relationship is known to exist with another stablecoin of Ethena, USDtb, which is supported by a tokenized fund from BlackRock.
In June, Janus Henderson announced a partnership direction, this asset management company with a scale of about 480 billion US dollars plans to incorporate USDe into its cash management strategy and explore distributing yield products through ETP.
Coinbase Ventures completed its first investment in Ethena, planning to bring related products to its more than 100 million users, while Anchorage Digital provides support on the institutional lending and custody side.
Launched in September, Ethena Pay, in a sense, is a response to the question of revenue-generating capability. Market analysis indicates that the logic of this product is similar to the revaluation path of ether.fi, aiming to transform the protocol from one that earns through bull and bear cycles into a new bank that generates revenue through everyday consumption fees.
Who is amplifying this round of market?
In the past month, a quicker and more direct force pushing ENA upward has also been sentiment.
On September 20, BitMEX co-founder Arthur Hayes publicly called for ENA, setting a target price of 0.5 US dollars.
In his article "Yen-quake," he mentioned that the US and Japan are working together to intervene in the yen exchange rate, and the Fed may adjust the FIMA mechanism to inject liquidity into the market. Money outflow would push up Bitcoin prices, which would in turn boost Bitcoin basis yields, making the yields of USDe attractive again, leading to a return of funds, and consequently, an increase in ENA.
However, Hayes has certain interests linked with Ethena. In a seed round financing of 6 million US dollars completed by Ethena in July 2023, Hayes's family office Maelstrom was one of the investors, with Dragonfly as the lead investor.
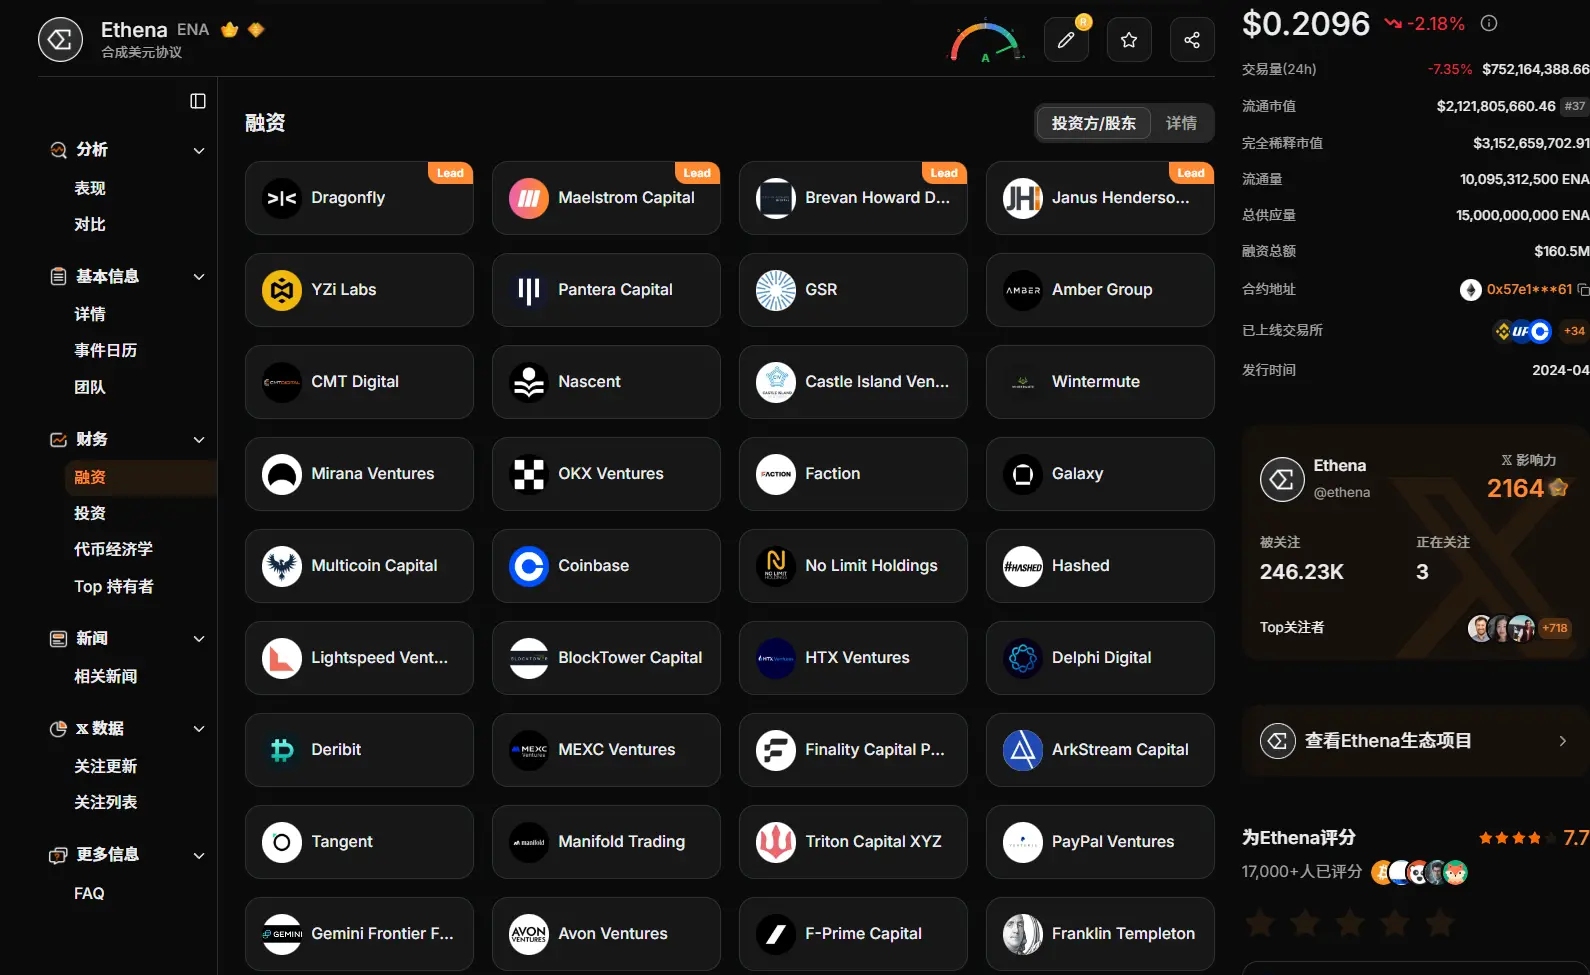
KOL BITWU also pointed out that ENA is still the largest position in Hayes's on-chain labeled address, and he had built the position a month prior to publicly calling for it, with unrealized gains reaching 146% at the time of the call. Hayes's calls often have the correct direction but wrong timing, and his words and actions frequently contradict.
As for whether this round of rebound can hold, it ultimately comes down to two points: whether the supply of USDe can reach the 7.5 billion US dollar threshold within a reasonable time to activate the buyback mechanism, and whether the tokens concentrated for unlocking on October 5 can be successfully digested by the market rather than becoming the starting point for a new round of selling pressure.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


