Original Author: Mario Chow
Original Source: IOSG Ventures
The stock price is the closing price on November 13, 2026; the Bitcoin price is $64,400 on November 16. In the text, MW refers to critical IT load, which is the actual power delivered to the servers. Gross MW refers to the total electricity consumption of the entire park, including cooling, typically 20% to 40% higher than the IT load.
TL;DR
Why shift. CoinShares values fully constructed and rented AI data centers at about $27 million per MW and estimates the value of unoccupied mining power capacity at under $3 million per MW. This ninefold difference is not solely due to grid connections; the former includes construction investments of $8 million to $15 million per MW; even after subtracting construction costs, the gap remains 4 to 6 times. Calculating operating profit per MW, mining with the current hash price could net about $230,000 in a year, while AI leases are around $1.9 million, meaning Bitcoin has to rise to about $250,000 to close this gap. The underlying issue is the electricity shortage for AI: it takes three to four years to connect a new power line in the hottest markets in the U.S., while miners already have powered connections. The midterm elections on November 3 made these connections scarcer, as Texas elected a governor who promised to halt data center approvals.
How to shift. Grid connections, substations, land, and permits can be reused, while almost everything else needs to be dismantled and rebuilt, costing about $8 million to $15 million per MW, similar to new builds. Miners are selling not the buildings, but the two to four years of waiting time for tenants to bypass.
Who is shifting. Eight publicly listed mining companies have signed for about 6.3 GW of IT capacity; on the morning after the election, Riot leased the entire 910 MW Corsicana site; Cipher also has 700 MW of gross power. About 1 GW is truly online. CoreWeave occupies 24% of the market, and there is no guarantor behind the rents. Riot's AI lab tenant (reportedly Anthropic) now accounts for 18%, almost as large as CoreWeave.
Revenue and costs. After deducting operational costs, disclosed leases with NOI range from $1.85 million to $2.15 million per MW per year; the NOI of Galaxy Helios II is estimated at about $2.3 million based on its profit margin. The annual return on construction costs is between 15% and 20%. Riot's Corsicana lease breaks this range with about 33%, as the data centers are built by tenants on parcels already powered by Riot. The nominal rent disparity primarily stems from lease structures rather than compensation for credit risk.
Impact. Several firms sticking with mining have sold about 40% of their Bitcoin, with selling pressure mainly on MARA. Riot sold 20,264 coins this year, leaving 2,418; MARA sold 13,597 post-quarter to settle Bitcoin-backed loans. MARA, CleanSpark, and Riot now hold about 36,000 coins, down from 60,500 in August, with approximately 20,400 from MARA most likely flowing back into the market. Hashrate decreased and then rebounded, with miner exit not weakening the network. Mining company stocks are no longer proxies for Bitcoin. After the election, they differentiated by state: Riot rose by 25%, while Bitcoin fell by 12%; a few companies waiting for project completions in Texas and Georgia dropped by 15% to 18%.
IOSG Perspective
- CoreWeave faces rental risks without guarantees, Texas presents a second risk. Galaxy charges CoreWeave the highest rent in the industry but offers the lowest return on construction, around 15% per year; CleanSpark rents to Meta at about 16%, and Hut 8 rents to investment-grade tenants at 17% to 21%. The weaker the tenant's credit, the more landlords should profit; in reality, it’s the opposite. CoreWeave accounts for 100% of Galaxy's AI business, about 53% of Core Scientific, and 28% of Applied Digital; Hut 8, CleanSpark, Riot, and TeraWulf have no exposure to it. CoreWeave's revenue on November 10 exceeded expectations, with shares soaring 25% the next day; however, its recourse debt increased by about $10 billion, reaching $41.6 billion, and by November 13, its share price had returned to $53.
- The election introduced a second layer of scrutiny. Approved, rented, and funded MWs increased, while those still waiting on Texas or Georgia approvals fell. Galaxy failed on both counts: its entire business relies on CoreWeave, and its Helios site is in Texas, with Helios II yet to lease. Before CoreWeave’s credit stabilizes and Texas’s moratorium has a clear end date, landlords with high exposure should be priced lower than those with low exposure. Core Scientific is the cleanest example of CoreWeave exposure; post-election, its share price stabilized because 485 of the 590 MW leased to CoreWeave are already under lease.
- By combining both layers of scrutiny, landlords can be divided into three groups. The first group consists of those who are leased, not in Texas or Georgia, and have secured financing: TeraWulf (New York and Kentucky, backed by Google for its Anthropic lease project), Hut 8's River Bend (Louisiana, with non-recourse bonds), and Applied Digital (North Dakota, noted bonds). The second group consists of those who are leased but are waiting on Texas or Georgia, with further phases still contingent on state-level approvals or unfinalized loans: Riot's Rockdale and Corsicana, Hut 8's Beacon Point, Galaxy’s Helios I, and CleanSpark's Sandersville. The third group has not yet leased or been approved: Galaxy’s Helios II, MARA’s Matagorda site, and Cipher’s reserve projects in Texas. The first group should have the smallest discount, and the third group the largest; Galaxy falls into both the second and third groups, coupled with CoreWeave exposure.
- The primary sellers of coins, as expected, are a few firms sticking to mining, with the remaining mainly being MARA. In August, the transformed landlords had almost no Bitcoin, while MARA, CleanSpark, and Riot had a total of about 60,500 coins, with all three needing to fund AI projects. Subsequently, two of the three sold. Riot sold 20,264 coins over the first nine months, totaling about $1.5 billion, mainly for data center construction, leaving only 2,418 coins by the end of September. After the quarter, MARA sold 13,597 coins at an average price of about $81,000 to pay off $750 million in Bitcoin-backed loans, indicating it would continue using Bitcoin to fund AI efforts. The three now collectively hold about 36,000 coins (around $2.3 billion), indicating they have sold about 40%, leaving 60%. Whether the remaining coins get sold depends on who needs cash. Riot's 2,418 coins are now inconsequential, as its cash and project loans will cover its expenses. CleanSpark's 13,530 coins haven't changed; its Sandersville project is funded by noted bonds, making them least likely to sell. However, it stopped issuing monthly production reports starting in October. MARA’s approximately 20,400 coins ($1.3 billion) are the key selling pressure to monitor: it stated it would continue selling coins to fund AI, and it might have to pay up to $600 million if its Texas site gets approved for power, plus it’s negotiating two leases that would also involve self-construction. The peak of inventory liquidation has passed, but it isn’t over.
- Mining company stocks are now credits trading on AI, with an additional layer of Texas licensing trading after the election. Transformed landlords follow the path of CoreWeave and Nebius, not Bitcoin: when Bitcoin rose in October, they fell with CoreWeave's bonds. From November 3 to 13, Bitcoin dropped by 12%, while Riot surged 25% due to a Texas lease for 910 MW where power has been approved; Galaxy, Cipher, and CleanSpark have projects still pending in Texas and Georgia, falling 15% to 18%. Investing in this basket of stocks involves betting on financing and state-level permits for AI data centers, with Bitcoin just a minimal component.
Why miners are shifting away
With rising coin prices, mining has actually worsened.
Hashprice refers to the expected daily earnings per PH/s of computing power (gross of costs), determining whether a miner can survive, and this number has been declining.
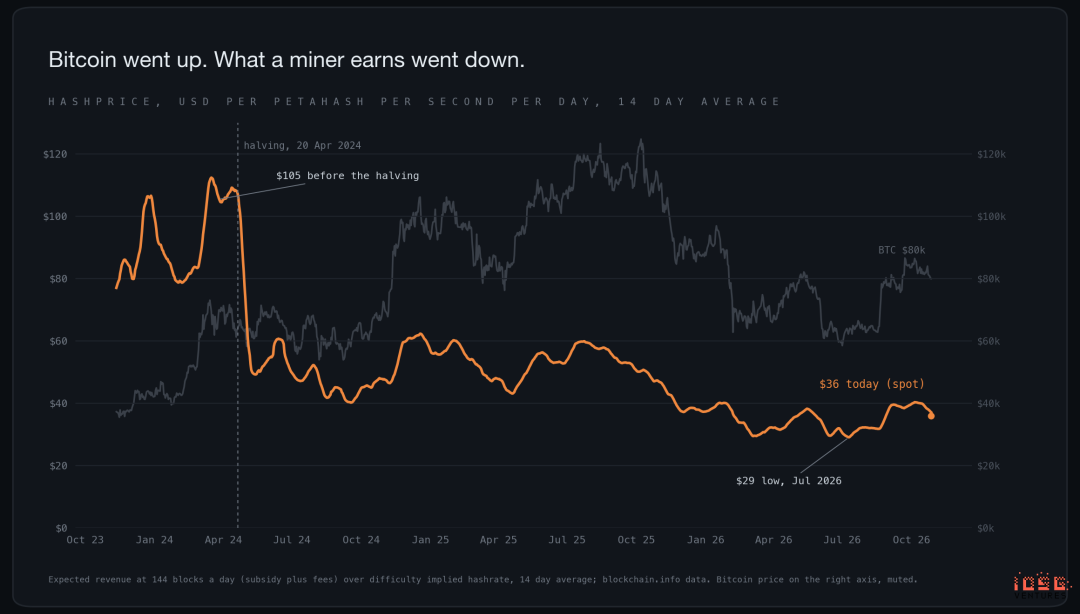
Before the 2024 halving, 1 PH/s could earn about $105 a day. It is now about $30, while Bitcoin prices have returned to those previous levels. The halving cut block subsidies in half, yet the total network has increased by about 70%, squeezing shares for each machine twofold. This is nearing the lows of last summer: during which hashprice briefly fell below $30, with CoinShares estimating publicly listed miners' average cash cost at $75,500 per coin, while Bitcoin hovered around $60,000, meaning the entire industry was mining at a loss.
Bitcoin rose to $84,000 in October, then fell to $64,400 this month. Neither movement changed much because the returns from the alternative route are too far apart.
The same 1 MW, two algorithms
The chart below uses hashprice of about $35 around late October; based on the current $30, the mining column will be even lower.
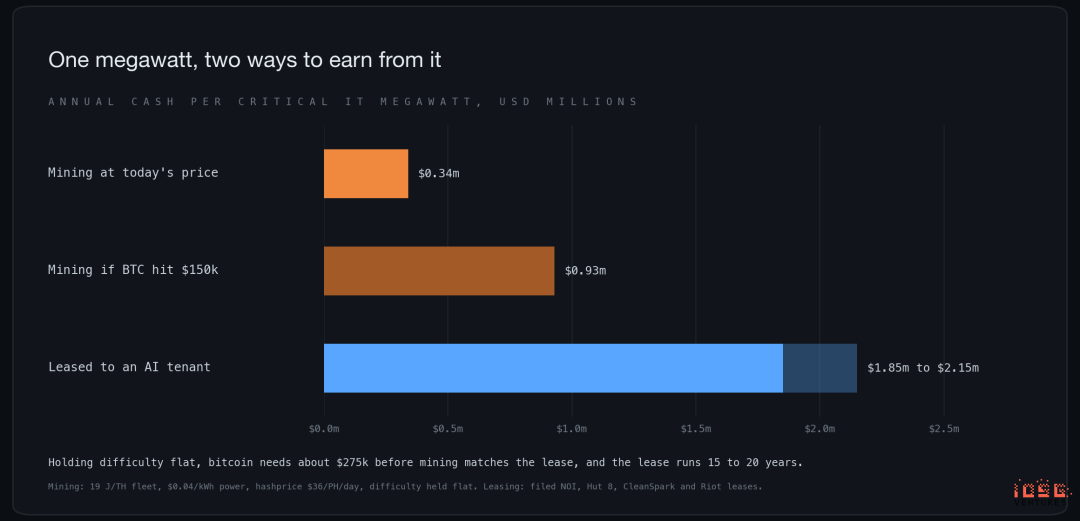
Operating profits per MW indicate that a new generation of mining machines could net about $230,000 a year after power costs based on the current hashprice, and the next generation would require additional investment. Renting to AI tenants, the same 1 MW could bring in $1.85 million to $2.15 million in NOI (net operating income), with a contract period of 15 to 20 years, plus annual rental increments. Even if Bitcoin rises to $150,000 with constant difficulty, mining would only net about $1 million a year, with no contractual guarantees.
This comparison highlights an advantage for leases: the $1.9 million NOI requires construction investments of $8 million to $15 million per MW, while mining merely needs about $800,000 for equipment. CoinShares's valuation cannot directly determine conclusions either. It values fully constructed, fully leased AI data centers at about $27 million per MW, and it values capacity that is electrified but unoccupied by miners at under $3 million per MW, comparing two asset types rather than the value of the same park pre- and post-rental. Excluding construction costs from the valuation of rented assets leaves $12 million to $19 million per MW, still 4 to 6 times the valuation of unoccupied assets; however, this does not account for construction completion risks and the two years prior to lease commencement. The direction is clear, but the exact multiples are not precise.
The most compelling evidence is how much miners are willing to pay to exit. Core Scientific spent about $42 million to cancel a new order for 15 EH/s mining machines. Keel (formerly Bitfarms) ceased mining in June. Galaxy transformed its Helios mine and recorded impairments.
How mining farms become data centers
Retain the sockets, rebuild the rest
After transformation, only items on the outside of the power meter, that is, the grid side, can be retained.
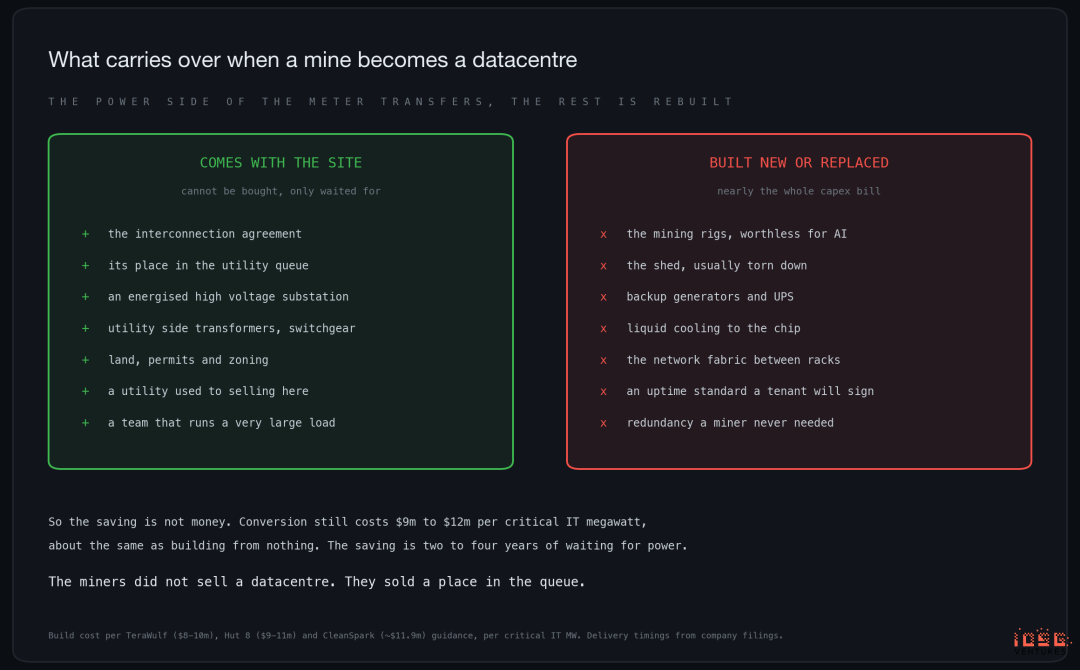
Everything outside the meter can be reused, while almost everything inside is rendered useless. ASIC miners are not useful for AI, and facilities usually also need to be demolished. When power prices rise, miners voluntarily reduce loads, so they have never installed backup generators or redundant power distribution, nor can they meet the online rate promises required by AI tenants. One GB300 cabinet from NVIDIA consumes 130 to 140 kW, while an ordinary server cabinet only consumes about 9 kW, requiring heat to be dissipated via liquid cooling pipes attached to the chips.
Thus, the transformation cost is around $8 million to $15 million per MW: TeraWulf estimates $8 million to $10 million, Hut 8 estimates $9 million to $11 million, CleanSpark around $11.9 million, and Galaxy's Helios II about $15.4 million, effectively equal to new builds. What is saved is not money, but time.
Three ways to sell MW
Landlords can lease out a shell, rent out computing power, or sell the park directly.
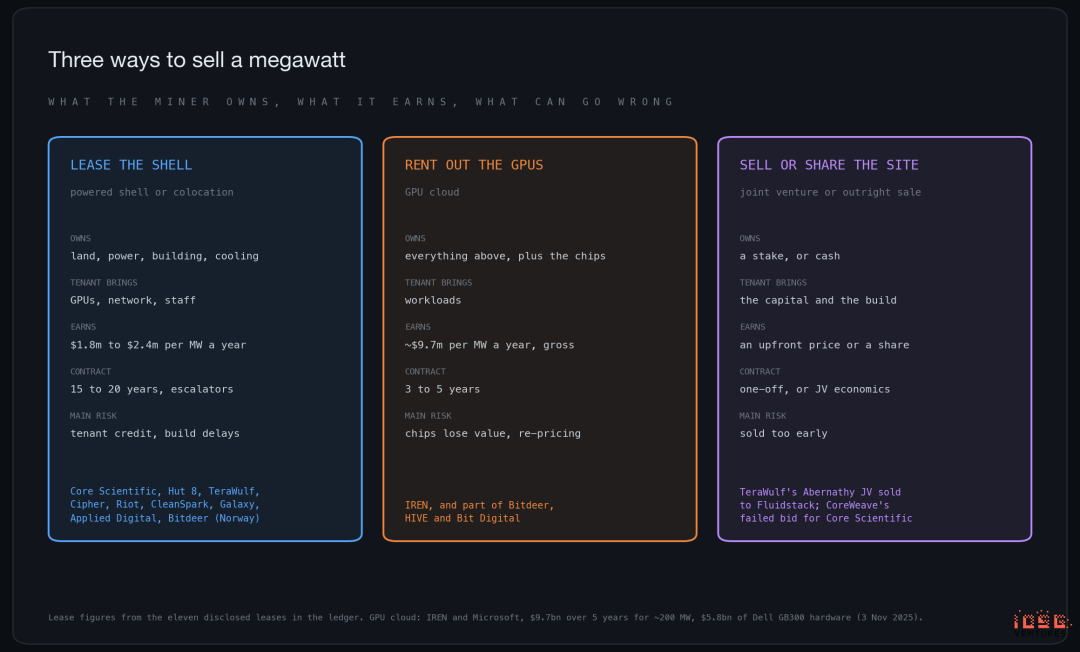
Most sales in the industry are for a “powered shell”: land, power, buildings, and cooling, with GPU, networks, and operational staff provided by the tenant. With such a division of labor, transformed mining companies can be valued like real estate firms. Riot's Corsicana lease goes a step further, selling “powered land”: Riot only provides land, power, and platform space, with the data centers built and operated by the tenants themselves.
IREN opted for the path of renting computing power, typified by its 5-year, $9.7 billion contract with Microsoft, needing $5.8 billion in Dell hardware purchases. Its revenue per MW is about five times that of leases, but most of the chip's value disappears within five years, and the contract duration is only one-third of that of leases. Comparing revenues per MW for IREN and landlords is a common error in this industry.
The third route involves selling off the park. TeraWulf sold $530 million worth of equity in its Abernathy joint venture project to Fluidstack, with $250 million already received in the third quarter. CoreWeave aimed for a whole acquisition of Core Scientific in 2025 but was voted down by Core Scientific's shareholders.
Where the money comes from
A 200 MW site, calculated at $10 million per MW, requires $2 billion and construction expenses about two years prior to leasing.
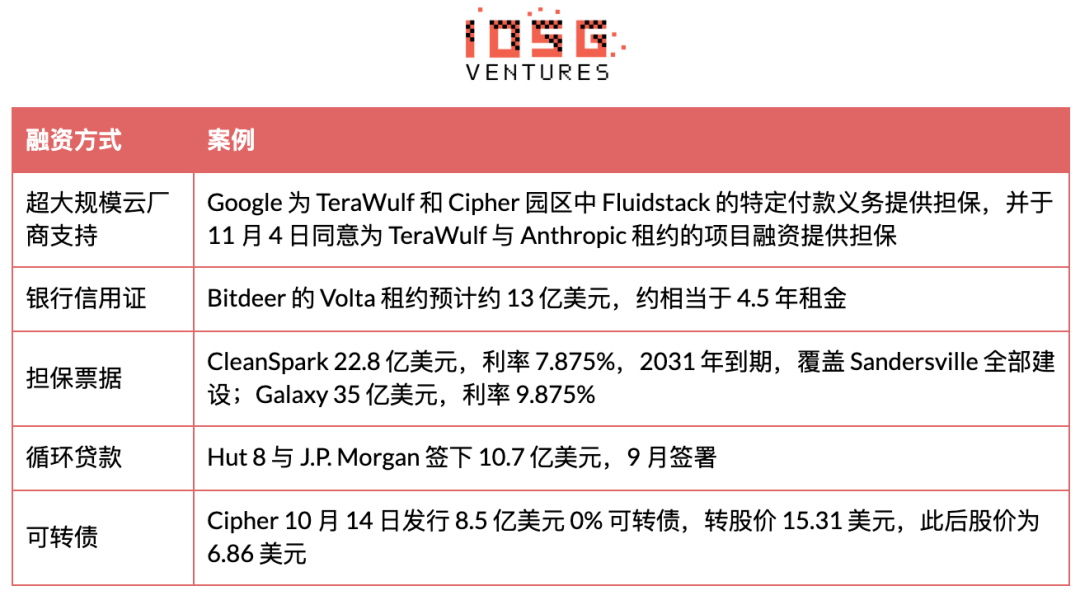
The time risk to watch closely is still Riot. Its $573 million bridge loan from Morgan Stanley matures on December 31, 2026, but the first 96 MW at Rockdale won’t commence until December 2027, while the investment-grade guarantees for this $9.1 billion lease are still being finalized. Riot had $950 million in cash and Bitcoin at the end of September, indicating no plans for stock issuance and is arranging project loans for Rockdale and Corsicana. This loan must be in place before leasing begins.
Who's doing it now
Landlords: Signing doesn’t mean completed construction
The Corsicana lease has made Riot the second-largest landlord by contracted capacity, but almost none are online yet.
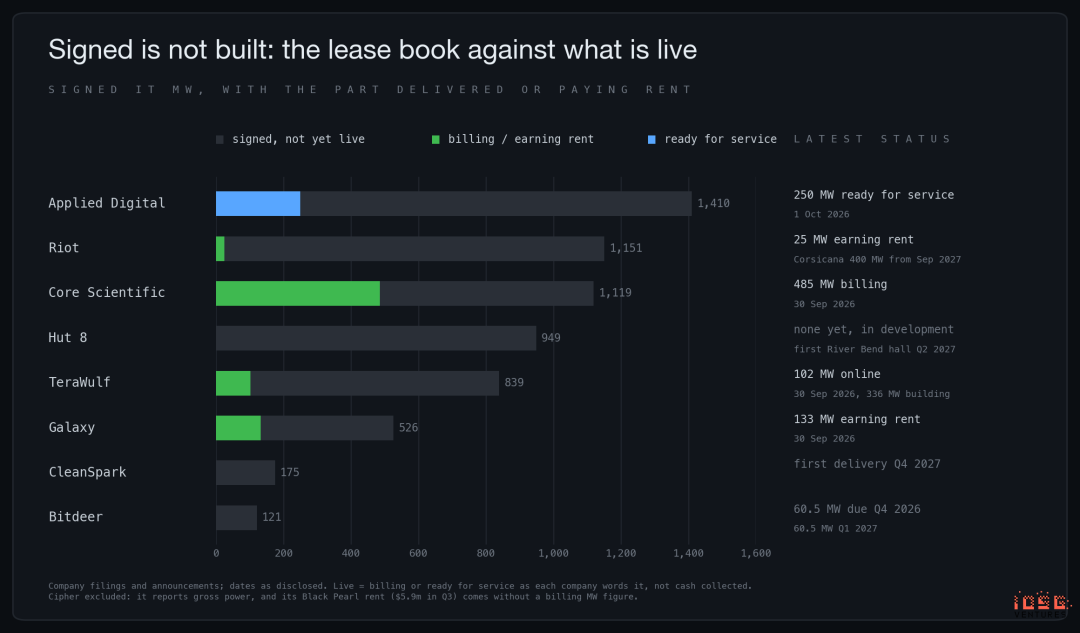
Contracted MWs include capacities that will not be delivered for several years; billed MWs are the parts that have already begun generating rent. Galaxy has rented 526 MW to CoreWeave, with 133 MW currently paying rent. The remaining 393 MW are not waiting empty for tenants, but have already been leased out and are under construction. Core Scientific had 485 MW billed as of September 30; it was 395 MW on June 30, and the remaining 100 MW at Dalton is expected to come online in early 2027. The grid connection only resolved one bottleneck, with further tasks including financing, construction, cooling, redundancy, and tenant acceptance still pending, so the low billed capacity amid the large future contracts does not indicate weak demand.
Cipher's 700 MW is gross power rather than IT load, so we haven’t counted it in capacity proportions. However, its documents revealed that Amazon's IT load in the Black Pearl lease is 216 MW, equating to an annual rent of about $1.7 million per IT MW. Black Pearl generated $5.9 million in rental income in the third quarter, marking Cipher's first rental income.
The largest lease in the industry emerged the morning after the election. On November 4th, Riot leased the entire 910 MW Corsicana site for 15 years at approximately $28 billion to the same AI lab in Rockdale. Prior to this, there hadn’t been any new leases since September 18; Cipher extended the Barber Lake lease to 20 years, increasing the contract value by $5.2 billion, but it didn’t add a single MW.
Tenants
With Corsicana, the portion rented directly by AI labs has more than doubled.
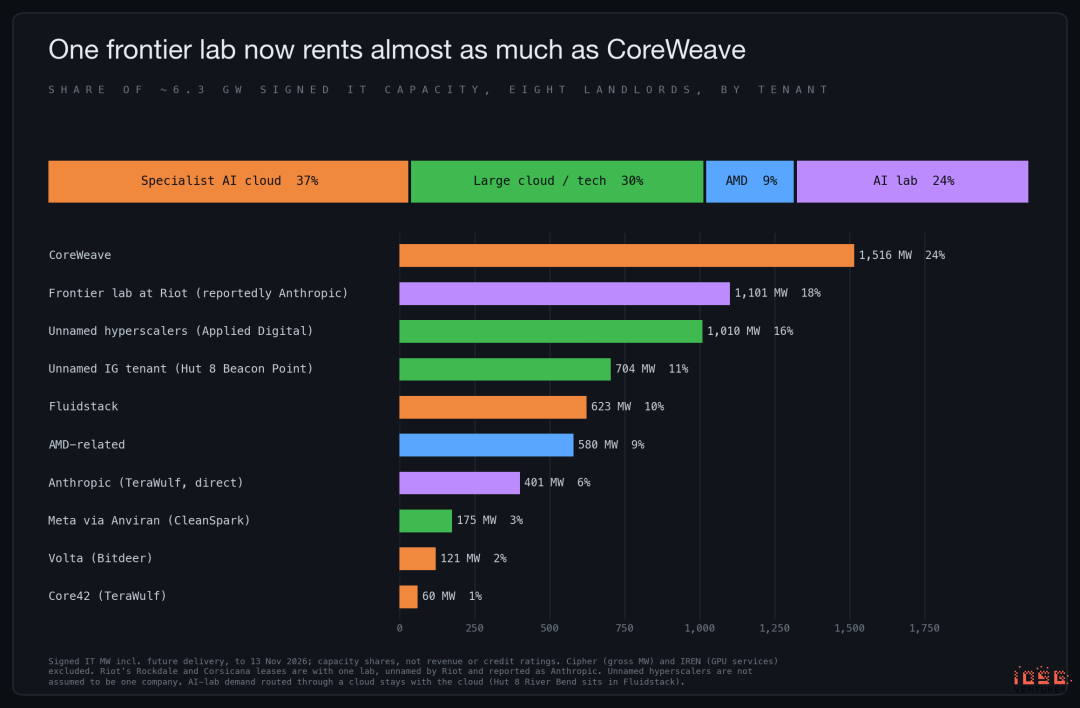
Specialized AI cloud (neocloud) remains the largest group of tenants, accounting for about 37% of the 6.3 GW. CoreWeave has rented 1,516 MW through Applied Digital, Core Scientific, and Galaxy, making up 24% of the total, while Fluidstack accounts for another 10%. Large cloud and tech companies make up about 30%, AMD-related arrangements account for 9%, and direct rentals from AI labs account for 24%, having been only 11% prior to Corsicana. If Riot's tenant is indeed Anthropic as reported, then Anthropic's direct lease amounts to about 1.5 GW, plus 245 MW rented through Fluidstack at River Bend, indicating terminal demand has already surpassed CoreWeave.
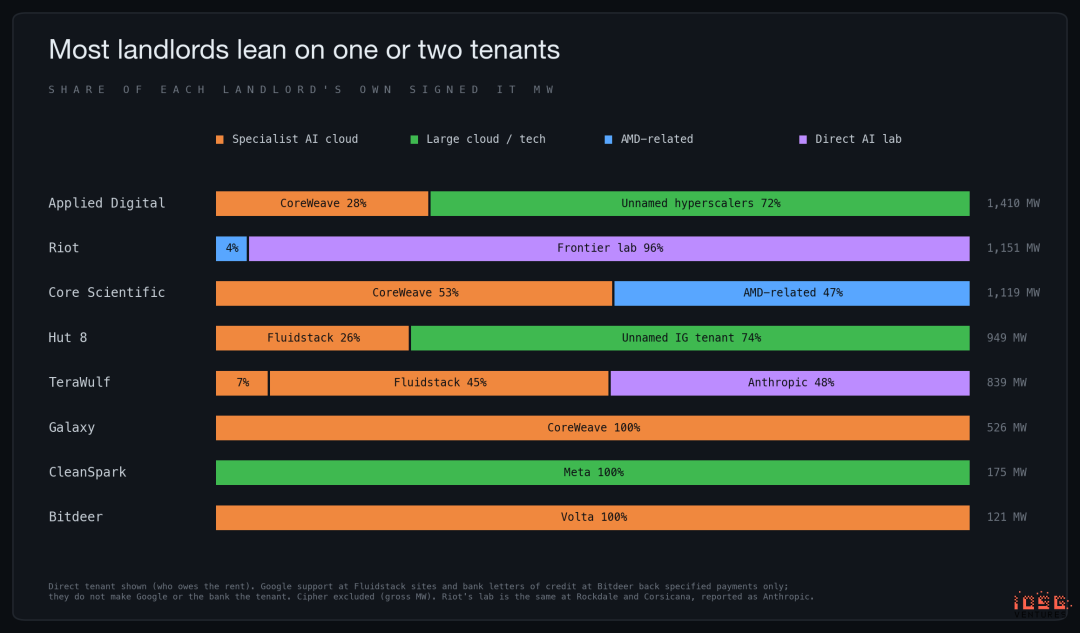
Each landlord has very concentrated tenants. Galaxy, CleanSpark, and Bitdeer each have only one tenant, while 96% of Riot's capacity comes from the same lab. The true concern lies with the concentration of CoreWeave, as the credit landscape has reversed since summer. Initially, concerns were about unrated AI labs. Subsequently, Anthropic secured $65 billion at a $965 billion valuation, reportedly informed investors of $16.8 billion in revenue for the September quarter, and submitted its IPO application on October 26, which is currently on the roadshow, with an estimated valuation of about $1 trillion. The real concern for the market is CoreWeave: rated B+, with recourse debt of $41.6 billion, increasing by about $10 billion in one quarter. By mid-October, its bond yields approached 15%, with 5-year CDS exceeding 1,000 basis points and remaining at this level before the November 10 earnings report. In this batch of leases, the greatest risk lies not with the labs but with the intermediaries leasing capacity to the labs.
A few still mining
The only few remaining large-scale miners are: Bitdeer at 82 EH/s, MARA at approximately 71 EH/s, CleanSpark at 50 EH/s, and American Bitcoin, part of Hut 8, at about 25 EH/s. They are also preparing a backup plan. MARA's 2 GW site in Matagorda, Texas has been categorized as “studied load” in ERCOT's Batch Zero process, and MARA plans to sign two leases by the end of the year, though it may be delayed until next year. CleanSpark's mining machines are now right next to Meta's lease in Georgia. Riot, nominally still considered committed to mining: mining still constitutes the bulk of its income, but it has leased out 1,151 MW and has nearly sold out its Bitcoin.
Revenue and costs
How much rent can 1 MW bring in
Nominal rents are calculated by dividing the contract value by the number of MW and the duration in years. NOI is the money left for landlords after deducting property operating costs, not accounting for financing, depreciation, and taxes. Under triple net leases, operating costs are borne by tenants, making the two numbers nearly identical; in leases that include services, landlords pay those costs themselves from higher rents, surrendering 10% to 20%.
Based on IT loads, nominal rents vary from about $1.44 million per MW per year (CoreWeave at Core Scientific) to about $2.6 million (CoreWeave at Galaxy’s Helios II). The same tenant appearing at both ends of the range indicates that nominal rents are clearly not a pricing determinant of credit. At Core Scientific, most of the room renovation costs are borne by CoreWeave, with Core Scientific’s economic input approximately $1.5 million per MW, thus the lower rents correspond to far lesser construction input. The figure below shows four leased agreements detailing both rent and NOI to clarify this.
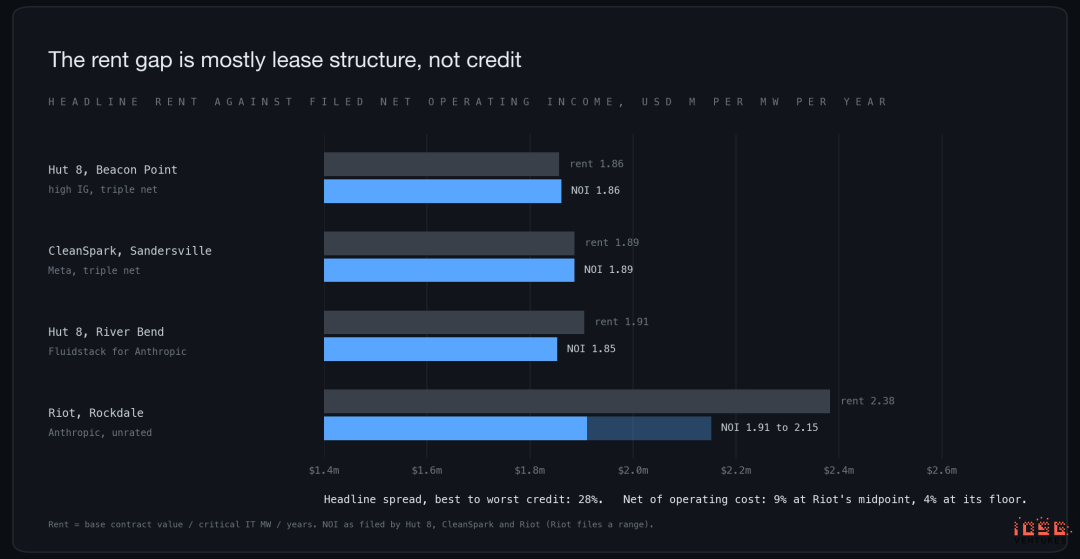
Riot's lease at Rockdale with an AI lab (reportedly Anthropic) has a nominal rent 28% higher than that of Hut 8's high-rated triple net tenant. After deducting operational costs, its median rent from Riot's disclosed range is only 9% higher, and at the lower end only 4% higher. The excess rent largely serves to cover the costs borne by the landlord, leaving almost nothing to compensate for weak credit.
Riot's Corsicana lease is the latest one and represents another type of product. The average annual rent for 910 MW is about $1.8 billion, equating to about $2 million per MW (including rental increments), with an NOI profit margin of 99%, falling within the Rockdale range. What changes are costs. Riot invests only about $6 million per MW, while complete construction would be $8 million to $15 million because the data centers are built and owned by the tenants. This is the first lease priced based on “approved Texas electricity” rather than construction. The signing date was precisely the morning after the election, and that election just made approved Texas power scarcer.
The timing might be more critical than credit. Amazon signed with Cipher by the end of 2025 at about $1.7 million per MW; Meta signed with CleanSpark nine months later at $1.89 million, both being triple net leases, both top-tier credit. Direct leases from AI labs signed mid-2026 (TeraWulf, Riot Rockdale, Bitdeer) range from $2.37 million to $2.43 million. The Corsicana signing in November is about $2 million, breaking this trend; it would be even lower when accounting for base period terms since its $2 million average includes rental increments, while other numbers do not include increments. Its covered construction is also much less. These are nominal figures under different structures, giving us clues to patterns but not definitive conclusions.
Cost returns
Construction costs have risen almost as fast as rents, so the return on construction remains stationary in a narrow range. Here, the cost return rate is the annual NOI divided by construction costs, not equating to shareholder returns.
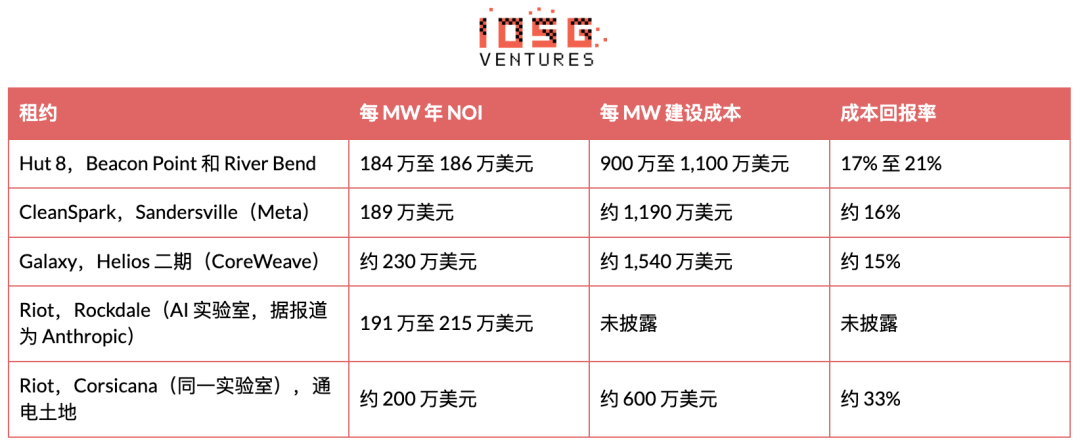
A building with a signed 15-year tenant achieves an annual return between 15% and 20%, representing a very good property business. Miners can earn this money because they hold scarce elements; Corsicana illustrates how much the element itself can earn when financed by tenants. The 33% is Riot’s own number, with the premise being the project loan's successful rollout, which is still being arranged. Galaxy, having the weakest tenant credit, landed at the lowest of the range: highest rents, most expensive construction, and thinnest returns.
How many are truly collecting rent
According to the latest disclosures, Core Scientific had 485 MW billed as of September 30. Galaxy had 133 MW generating income as of September 30, which remained unchanged for the entire quarter; its phase II would begin leasing in the second quarter of 2027. TeraWulf had 102 MW online as of September 30, with another 336 MW under construction. Applied Digital had 250 MW deliverable from October 1, guiding to reach 300 MW by year-end. Cipher received its first rent at Black Pearl in Q3, but did not disclose the MW figure; Amazon's six-phase delivery ranges from September 30 to February 28, 2027. Riot's 25 MW for AMD has been generating rental income since the second quarter.
The rest are delivery pipelines. Bitdeer has two phases of 60.5 MW, scheduled for delivery in the fourth quarter of 2026 and the first quarter of 2027, Hut 8's River Bend first room is expected in Q2 of 2027, Riot's Rockdale lab capacity should be ready by December 2027, and Corsicana will be delivered in three phases from September 2027 to July 2028, with CleanSpark's first rental income expected in Q4 2027. The dates and milestone criteria for these figures vary, so we do not total them into an industry percentage.
Impact
On Bitcoin: A few firms sticking to mining are selling
First, let’s lay out the most compelling argument from shorts. Blockware reports that public miners’ Bitcoin inventory has dropped from about 127,000 at the beginning of the year to about 99,000 in mid-August, equivalent to about $1.8 billion in net sales used for data center construction. MARA is the largest holder and is also the loudest about “just stockpiling and not selling”; in March, it changed its policy to allow selling reserves, seeing its holdings decrease from 53,822 to 35,577 coins during the following six months. Blockware believes this selling pressure is one of the underestimated reasons for Bitcoin’s weakness in 2026, making this argument valid. Moreover, this trend continues.
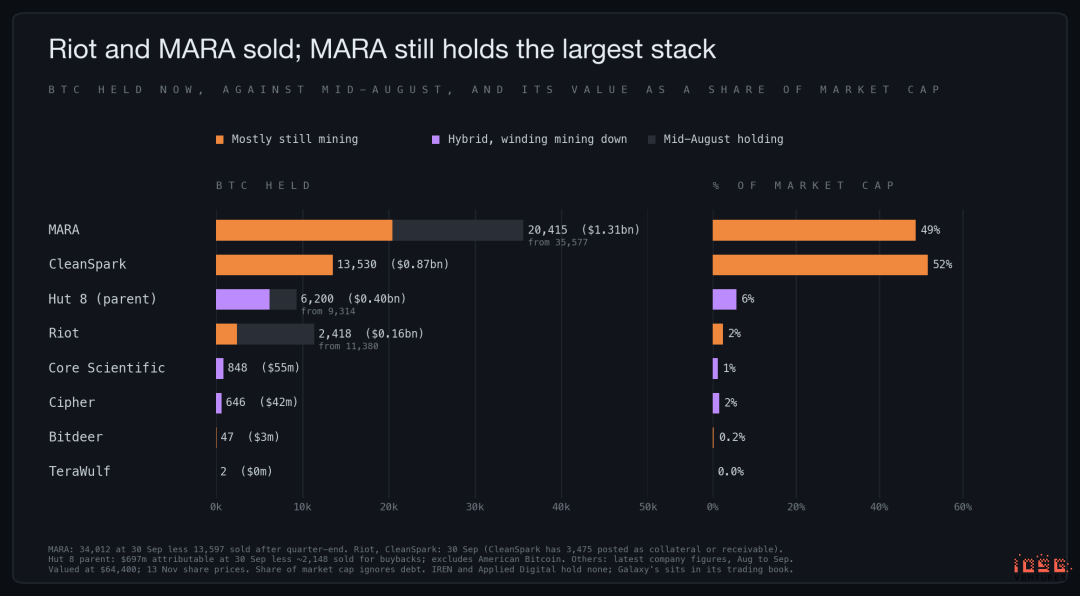
Transformed landlords have had little to sell for a long time: Core Scientific and Cipher each hold fewer than 1,000 coins, amounting to around 1% of their market value, while TeraWulf, IREN, and Applied Digital are virtually at zero. So the selling pressure has shifted to a few companies still mining and starting to build AI projects. Riot has sold 20,264 coins in the first nine months, mainly for data center construction, leaving only 2,418 coins by the end of September. After the quarter ended, MARA sold 13,597 coins at an average price of around $81,000 to repay $750 million in Bitcoin-backed loans, and the pledged coins were subsequently released. Hut 8 sold about 3,100 coins for stock buybacks. CleanSpark’s 13,530 coins were the only ones that didn’t decrease among the stalwarts; it stopped issuing monthly production reports in October. MARA, CleanSpark, and Riot now collectively hold about 36,000 coins, valued at about $2.3 billion at current prices, down from 60,500 coins in August. This marks a 40% reduction, not a complete sell-off. MARA still has about 20,400 coins and stated it would continue selling coins to fund AI; CleanSpark’s construction is funded by notes, while Riot's remaining 2,418 coins are now inconsequential.
Inventory is not the sole supply. The entire network issues about 450 new bitcoins each day, and how much miners choose to hold is up to them; the transformation has pushed this choice towards selling. MARA revised its strategy in 2025 to allow selling mined coins, expanding to reserves in 2026; Riot has sold more Bitcoins this year than it mined. CryptoQuant data shows that on October 26, miners transferred 21,140 coins to Binance, marking the sixth day since February that the single-day transfer exceeded 20,000 coins, with miner reserves nearing five-year lows. This flow also includes private miners and mining pools, and transferring to exchanges does not equal selling; it suggests coins are moved to sellable locales, not necessarily indicating that they have been sold. After that, Bitcoin fell from about $84,000 in late October to $64,400, the lowest since August, amid outflows from spot ETFs, hawkish statements from the Federal Reserve, and selling in AI stocks after NVIDIA announced Jensen Huang's resignation as CEO on November 12. Miners selling coins added to this round of declining supply, but it was not the cause.
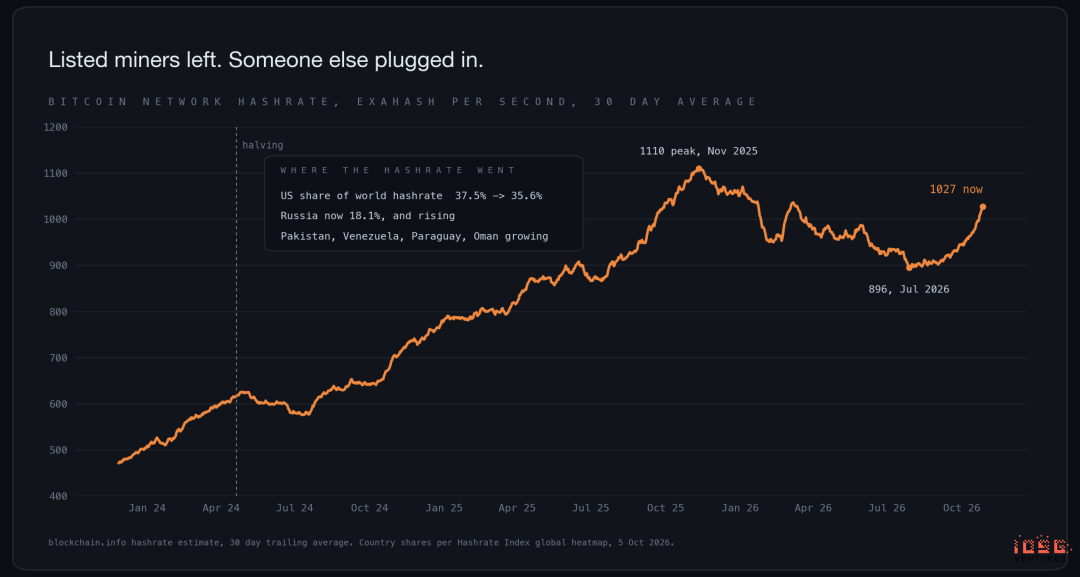
The network smoothly absorbed this exit. Hashrate fell 19% from its peak last November to July this year, then returned to above 1,000 EH/s in October, estimating around 965 EH/s based on mid-November difficulty. Difficulty adjustments made a difference: the remaining miners could mine more Bitcoin per unit of hashrate after publicly listed miners shut down, and elsewhere new production was being ramped up.
The more long-term issue is the security budget. This year, transaction fees only accounted for 0.63% of miners' income, consistently below 1% for the fifteenth month, with revenue almost entirely reliant on block subsidies, which are set to halve again in 2028. Adam Back observes that mining and AI represent an arbitrage, which will ultimately reach a balance where returns on both sides are equal. This year's rebound in hashrate supports his view. The real test will be the 2028 halving: at current coin prices, even if electricity costs only $0.04 per kilowatt-hour, the new generation of mining machines will not even cover their power costs, leading to more miners transferring power to AI. This year's experience shows that the network can digest the changes because whenever someone exits, someone else shows up to take their place.
On the crypto market: Mining company stocks are no longer Bitcoin trades
Since August 3, Bitcoin has been rising, while every mining company has been falling.
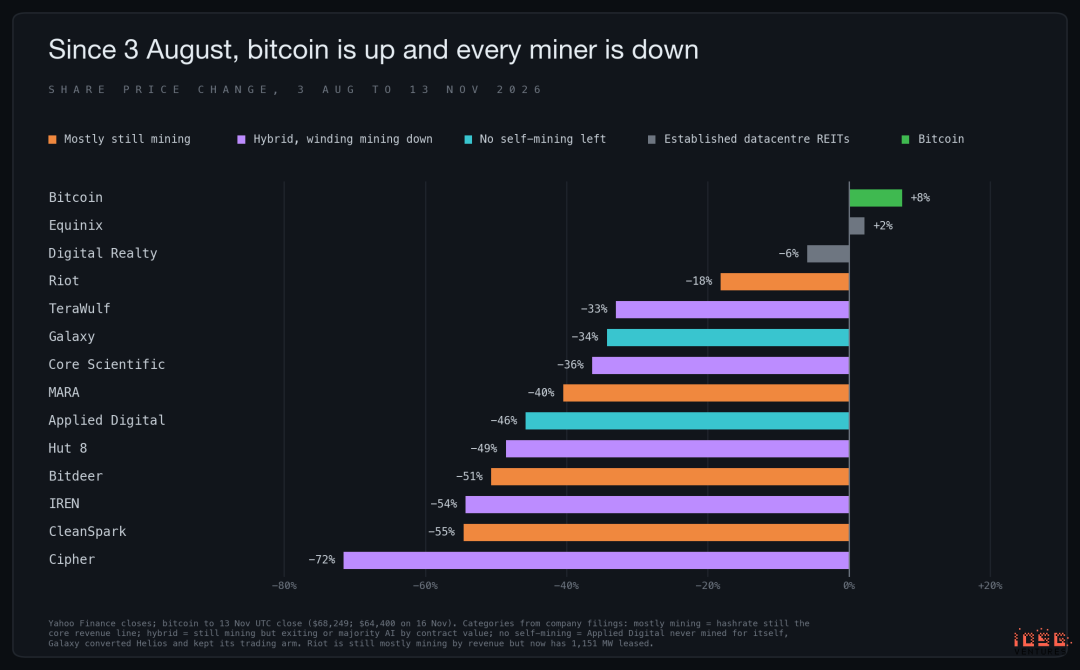
From August 3 to November 13, Bitcoin rose 8%, while every mining company fell, with declines between 18% for Riot and 72% for Cipher. Those still mining and those who have already transformed have both suffered equally; thus, the market is not punishing transformation. There are five reasons. One, the timing mismatch: mining stocks reached peaks in June, while Bitcoin only found a bottom around $63,000 in early August. Two, every company, including the holdouts, needs funding for AI projects, and stock prices are determined by that funding. Three, the October credit turmoil around CoreWeave affected all targets associated with AI data center debt. Four, Bitcoin's price increase seems less impactful because hashprice has never clearly exceeded $35. Five, the November 3 election discounted all projects waiting on Texas or Georgia approvals. Meanwhile, Digital Realty and Equinix remained between -6% and +2%, indicating that the issues lie within the mining companies: financing, permits, delivery, and tenant credit.
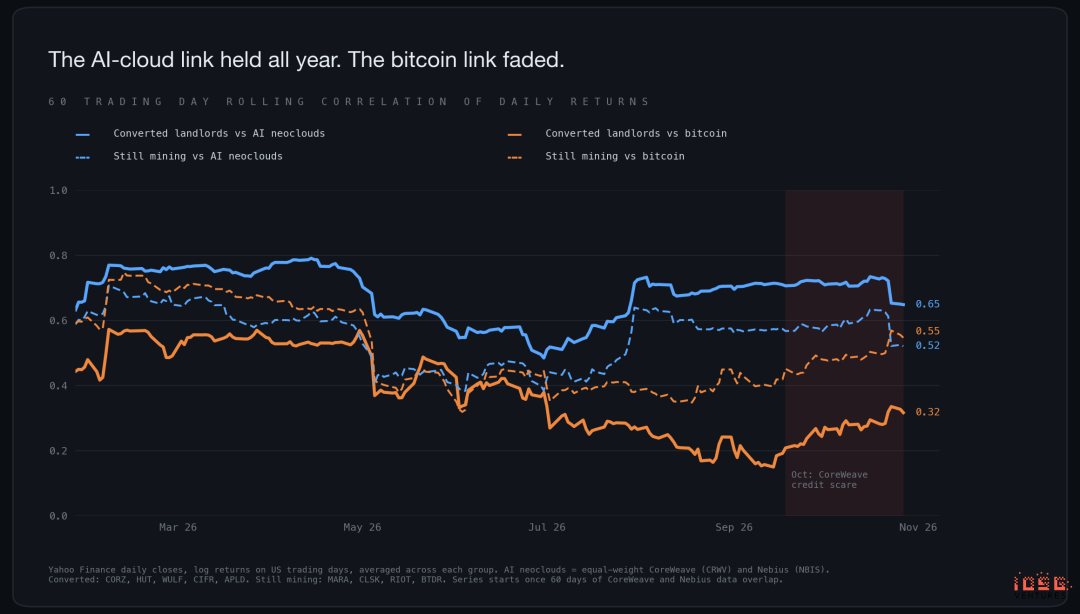
According to a 60-day rolling correlation, transformed landlords have remained between a 0.6 to 0.8 correlation with CoreWeave and Nebius for the entire year, tighter than with Digital Realty or Bitcoin. What has been severed is the relationship with Bitcoin, dropping from about 0.55 in the spring to 0.15 by mid-September. According to CryptoSlate, Hut 8's beta with Bitcoin dropped from 1.18 to 0.53, and Cipher's from 1.13 to 0.58.
The election further split this sector. From November 3 to 13, Bitcoin fell 12%, while Riot rose 25%, Core Scientific increased by 2%, and TeraWulf by 1%; Galaxy fell 15%, Cipher by 16%, and CleanSpark by 18%. Bernstein lowered the target prices for seven mining companies by 35% to 54%, valuing AI hosting businesses at a 12 times EBITDA multiple due to tightening in capital markets and uncertainties in Texas. Morgan Stanley favors TeraWulf, Hut 8, and Applied Digital more, citing their parks outside Texas, even though Hut 8's Beacon Point is also in Texas.
This round of selling started with companies renting out AI hashrate financed by debt and now has spread to the entire AI sector. Since August 3, CoreWeave has dropped 38%, Nebius 46%, and NVIDIA 21%, with much of NVIDIA's drop occurring after the CEO's resignation announcement. On October 14, CoreWeave bonds were sold off, while Cipher priced its convertible bonds the same day; Cipher dropped 12%, with most stocks in the sector falling 5% to 10%. The most well-known mining ETF, WGMI, now has its top holdings as Cipher, Nebius, CoreWeave, and Hut 8, two of which have never mined a single coin. For crypto investors, this basket of publicly listed miners is no longer a Bitcoin exposure but carries AI infrastructure credit risk, with a minimal Bitcoin component.
On AI: Real capacity, mainly for training
JLL estimates that North America has about 66 GW of data center capacity under construction; however, according to BNEF, the maximum new annual load from U.S. grids is only about 7.1 GW. The share of contracts that miners hold in the genuinely power-usable capacity expected before 2029 is significant, given that the grid connections are already in place. The midterm elections made this clearer: new governors in Texas, Georgia, and Ohio campaigned on suspending data center construction, making existing connections with contracts more valuable. The limitations will be addressed in the next section.
Risks
Texas. The AI parks of Riot, Galaxy, and Cipher are all in Texas, as are Hut 8’s Beacon Point and MARA’s new facilities. Just Riot, Hut 8 Beacon Point, and Galaxy account for 2.4 GW, representing 38% of contracted total capacity, not including Core Scientific's facilities in Texas and Cipher. The pause button has already been pressed under the Republican governor's administration. On August 3, Greg Abbott ordered an audit of large load connection queues, after which ERCOT immediately halted Batch Zero inquiries and new power approvals for large computational loads; on September 21, he also froze state environmental permits for data centers. The market had originally expected him to ease restrictions after the election. However, on November 3, Democrat Gina Hinojosa won, promising to halt all data center approvals until new laws are passed by the state legislature, with no end date for the moratorium. She will take office on January 19, a week after the state legislature convenes. Her power has boundaries: the public utility commission members are all appointed by Abbott, her nominated choices require two-thirds approval from the state Senate, where Republicans still hold a 19 to 12 majority. Our judgment is the halt will at least extend until mid-2027, with the final result being stricter conditions rather than a ban. The next key dates are the ERCOT audit report on December 10 and the public utility commission meeting on December 17. The already approved capacities have stabilized: when Riot signed for Corsicana, the power had already been approved. The risk exists in the portion still needing connections or permits: Galaxy’s Helios has an additional 830 MW that is still not leased; MARA’s Matagorda site's payments depend on power approval; and the backup power permits required for contracted projects. In Georgia, where CleanSpark's Meta lease is located, the new governor hopes for a statewide temporary halt, with the public utility commission also turning Democratic majority in 2027.
Demand shifts toward inference. These parks are inherently training grounds: miners choose locations for cheaper power, usually far from users. Gartner expected this year for AI-optimized cloud service spending on inference to surpass training at $23.3 billion to $19 billion, with inference expected to account for 59% by 2027. OpenAI has already scaled back some self-built plans, abandoning the 800 MW Abilene expansion in March, and suspending Stargate UK in April, although capacities from Abilene and Norway have been taken over by Microsoft, indicating demand is shifting rather than disappearing. The opposing argument holds weight: batch inference, agents, and reinforcement learning are not sensitive to latency, leaning towards a blend of loads. However, a 15 to 20-year lease effectively bets that both will continuously overlap.
Intermediary credit. About 37% of the capacity is leased to specialized AI clouds, which then rent it to labs. CoreWeave occupies 24%, with no guarantor behind the rent, holding recourse debt of $41.6 billion that was briefly priced under distressed conditions in October; management now states they will no longer issue unsecured bonds at current yields. Fluidstack occupies 10%, being an un-rated private company; Google only supports specific obligations for TeraWulf and Cipher but does not cover the overall. Bitdeer’s Volta still depends on conditionally attached bank letters of credit. If an intermediary collapses, landlords will be left with half-built buildings with only one tenant, while the end labs never signed contracts with them.
Financing. Most of these leases haven't been paid for; funding primarily comes from stocks which have dropped over a third since August, or debt priced against CoreWeave yield spreads. VanEck estimates an industry funding gap approaching $50 billion, with Bernstein also noting a tightening in capital markets. Hut 8's unrestricted cash fell to $157 million during the quarter, Bitdeer had $214 million at the end of September, while Tydal has several hundred million remaining capital expenditures. Riot's bridge loan maturing on December 31 is the latest test.
Conclusion
Transformation is real, and decisions have mostly been made. The grid connections in miners' hands are the most scarce element in AI construction. Once built and leased, a park is valued at about $27 million per MW without tenants at under $3 million; deducting construction costs, rented connections still hold four to six times the value. Bitcoin must rise to about $250,000 to change the operational numbers, hence even holdouts are preparing for the backup.
The election elevated the price of this element, also splitting it into two. Adding 1 MW now is more expensive and slower in the U.S., thus the approved, leased, and financed MWs are more valuable, while the MWs still awaiting Texas or Georgia approvals are less valuable. The Riot Corsicana lease signed the morning after the election is the clearest pricing for the former: tenant-built data centers have a cost return rate of about 33% annually.
What’s still incomplete is construction. About 6.3 GW is contracted, around 1 GW is online, and the rest need financing over the next one or two years. With cost returns of 15% to 20% per year, these leases are good business, with the rental differentials between strong and weak tenants primarily arising from lease structure. This provides some reassurance, but also highlights the problem: the landlord with the greatest CoreWeave exposure hasn't received additional compensation as a result.
For Bitcoin, inventory liquidation has passed its peak but isn't over. The transformers sold first, followed by Riot and MARA. The three remaining holdouts now collectively possess roughly 36,000 coins, with MARA’s approximately 20,400 coins most likely to continue entering the market. Hashrate has rebounded; the network has thus far absorbed this exit. For crypto investors, mining company stocks no longer offer a route to holding Bitcoin. They are now backed by AI infrastructure's credit risk and the Texas permit risk, leaving Bitcoin as only a minimal component.
Methods and notes
Capacity statistics as of November 13, 2026, account for disclosed AI leases and exclude IREN's GPU cloud contracts. Contracted capacity includes portions to be delivered in the future. Deliverable, delivered, and billed figures are listed according to the companies' own declarations; this varies by company, and we do not calculate overall industry billing percentages. Capacity proportions are based on contracted IT MW proportions, not income proportions or credit ratings. Unnamed hyperscale cloud vendors are not assumed to be the same company, and demand from AI labs leased through cloud vendors remains under the cloud vendor category. Riot has not disclosed tenant names for both of its lab leases; Bloomberg reports that Anthropic is the tenant for Rockdale, while Riot states Corsicana is with the same lab.
Cipher’s disclosed 700 MW is gross power rather than IT load, and therefore is not included in capacity proportions. According to Cipher's investor materials from February 2026, Black Pearl has 300 MW gross power, 216 MW critical IT load, hence Amazon's 15-year $5.5 billion contract equates to approximately $1.7 million per IT MW (about $1.22 million per gross MW). Cipher began renting at Black Pearl from August onward but did not disclose the billed MW numbers.
Nominal rents are calculated based on the contract value during the base period divided by critical IT MW and the number of years, excluding rental increments; Corsicana is an exception as Riot only disclosed the average rent including increments. NOI is solely based on numbers disclosed by companies from Hut 8, CleanSpark, and Riot. Galaxy's phase II NOI is calculated using more than 90% of disclosed profit margin multiplied by disclosed revenue. Cost returns are based on construction cost guidance from respective companies; Corsicana uses Riot's estimated $6 million per MW, which includes $4 million repaid to tenants.
Texas' share statistics include Riot (Rockdale and Corsicana), Hut 8 Beacon Point, and Galaxy Helios; they do not include Core Scientific's parks (separated disclosure was not provided) and Cipher.
Mining economics assume miner efficiency of 19 J/TH (52.6 PH/s per MW), electricity price of $0.04 per kilowatt-hour, full-time operation, unchanging difficulty, calculated only with income minus electricity costs. Hashprice is based on the expected income calculated from daily 144 blocks and total network hashrate difficulty; current numbers use mid-November difficulty at 134.8T and Bitcoin price of $64,400. Correlation is based on daily logarithmic returns on U.S. trading days. Bitcoin holdings are the latest disclosures from companies at the date depicted, valued at $64,400.
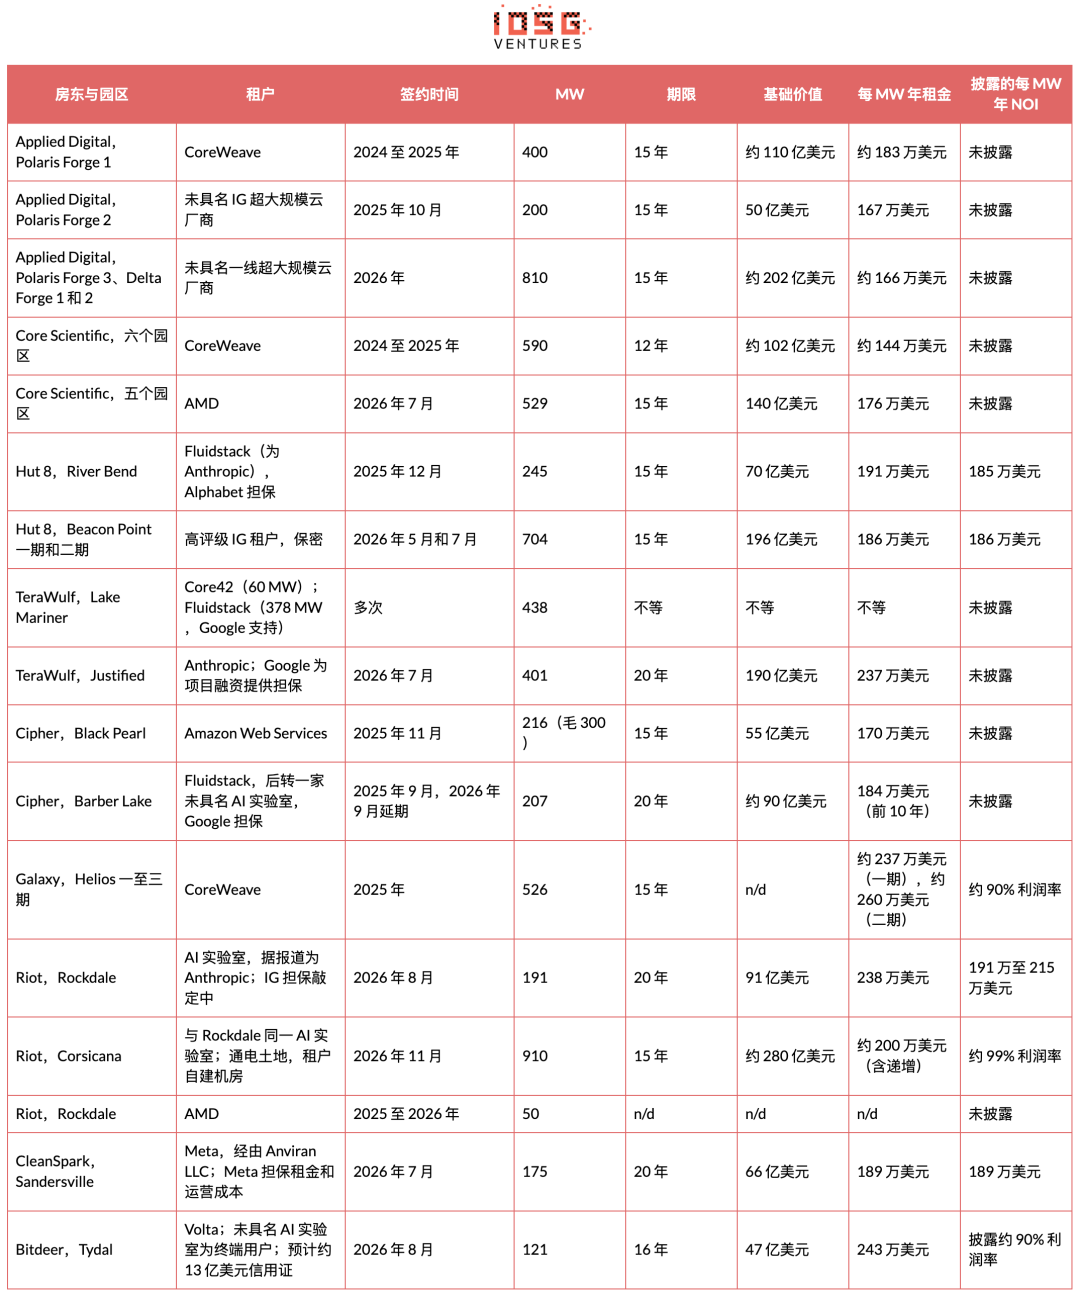
Lease Details
IG indicates investment-grade, n/d indicates no disclosure. Base value is the contract value in the base period. “Not disclosed” means there isn't an NOI figure findable in the consulted documents.
Sources
Mining Economy and Network
- CoinShares, Bitcoin mining report Q2 2026
- Hashrate Index, September 2026 lookback
- Blockware Intelligence, public miners sell about 28,000 BTC, and CoinDesk on the $1.78bn of selling pressure
- CoinDesk, miners selling BTC to fund the AI transition
- CryptoQuant, miners send 21,140 BTC to Binance
- Charles Edwards and Adam Back on the AI pivot and security
- Network data: blockchain.info and the mempool.space API
Market and Credit
- CryptoSlate, miners no longer pure crypto proxies
- WGMI holdings
- CoreWeave: Q3 2026 results, Tech Times on recourse debt, CNBC preview on debt, 10 November, Q2 2026 results
- CNBC, CoreWeave CDS at distress levels, 15 October, Bloomberg, CoreWeave risk gauge at a record, 15 October, Bloomberg, CoreWeave bonds tumble into distress, 14 October
- Anthropic Series H; Reuters, 14 October 2026, "Anthropic's Q3 revenue surges 45% to nearly $17 billion"; Anthropic S-1, 26 October 2026; Reuters on the IPO valuation target, 10 November
- Bitcoin and Nvidia in November: CoinDesk, 13 November, Yahoo Finance on the Nvidia CEO change
- Analysts after the election: CoinDesk on miner target cuts, Yahoo Finance on Bernstein's cuts, Reuters via The Star on sector moves
- Market data: Yahoo Finance daily closes to 13 November 2026
Electricity, AI Demand, Texas, and Elections
- JLL North America datacentre midyear 2026 via Network World
- BNEF via Bloomberg Law, US datacentre power demand
- GB300 NVL72 rack power
- Gartner, AI-optimized IaaS forecast, 10 August 2026
- OpenAI's pullbacks: Bloomberg on Abilene, CNBC on Stargate UK, CNBC on Norway
- Texas: Utility Dive on the interconnection pause and the ERCOT audit, Baker Botts on Batch Zero, Texas Tribune on the permitting halt, permits issued since and Hinojosa's plans, 4 November, Beveridge & Diamond, Texas Data Center Watch on what is paused
- Election: CBS Texas on the Texas House flip, Georgia Recorder on the Georgia PSC, Scripps News on governors and data centers
- The Block, Bernstein's "Follow the Gigawatts"
- CoinDesk, VanEck on the $50bn funding gap
Company Documents and Announcements
- Applied Digital: fiscal Q1 2027 results, fiscal Q4 2026 results
- Core Scientific: Q3 2026 10-Q summary, Q3 2026 call, Q2 2026 results, Q2 2026 deck, CoreWeave HPC agreement, June 2024, AMD partnership, 529 MW
- Hut 8: Q3 2026 results, Q2 2026 10-Q, $1.07bn revolver 8-K, River Bend lease, Beacon Point second lease
- TeraWulf: Q3 2026 results, Q2 2026 investor presentation, Anthropic lease at Justified, Fluidstack and Google support (DatacenterDynamics)
- Cipher: Q3 2026 business update, Black Pearl deck, February 2026, investor deck, 13 October 2026, Barber Lake amendment, $850m convertible notes
- Galaxy: Q3 2026 results, Q3 2026 overview deck
- Riot: Q3 2026 results and Corsicana lease, Q3 2026 10-Q, Q2 2026 results and Rockdale lease, Morgan Stanley facility 8-K, The Block on Bloomberg's report naming Anthropic
- CleanSpark: Sandersville lease, investor presentation naming Meta, September 2026, notes indenture, $2.276bn senior secured notes, September 2026 operational update
- Bitdeer: Q3 2026 results, Tydal lease with Volta
- MARA: Q3 2026 shareholder letter, Q3 2026 10-Q, Texas site acquisition 8-K
- IREN: Microsoft AI cloud contract, fiscal 2026 10-K
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


