Anthropic CEO Dario Amodei once wrote that creating a powerful AI is like “gathering a group of geniuses in a data center.” However, the latest IPO prospectus released by the company reveals another side of reality: to achieve this vision, Anthropic relies on a fragile and high-risk financing mechanism.
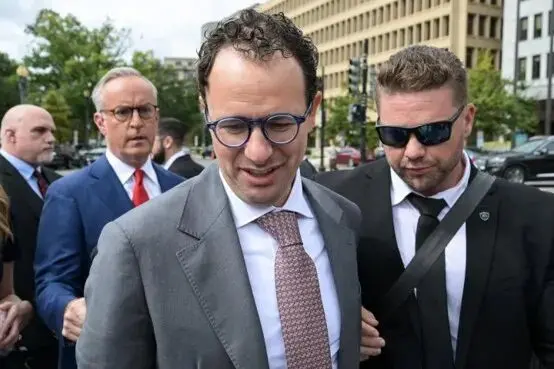
Anthropic CEO Dario Amodei. Image Source: Oliver Contreras—AFP via Getty Images
This week, Anthropic updated its prospectus, adding third-quarter financial data. Due to the continued rise in computing costs, the company's profit margins are shrinking; at the same time, the company disclosed additional commitments for data center construction expenditures, planning to invest as much as $895.4 billion cumulatively by 2045.
Some suppliers that provide chips and cloud services to Anthropic are also financing parties for related procurement projects. For example, Broadcom finalized a $63 billion equipment financing agreement: should Anthropic default, Broadcom will bear the corresponding losses; after all equipment has been delivered and put into use, the maximum potential liability for Broadcom could reach about $43 billion.
With these types of backstop clauses, Anthropic can obtain computing resources without making full upfront payments for equipment. Google and AMD also tie part of their funding to Anthropic leasing or deploying their hardware. However, if AI demand decreases, hardware manufacturers, facing pressure on their own revenues and market valuations, must still fulfill their guarantee compensation obligations and repay funds to lenders and partners.
Who bears the risks?
In the $63 billion deal announced on October 26, Bank of America, Citigroup, Morgan Stanley, and Blackstone will jointly invest to establish a new company responsible for procuring Broadcom chips and network equipment, which will then be leased to Anthropic, with equipment expected to be delivered in 2027. Anthropic will pay rent in installments, while investors will recover their principal through rental payments.
If Anthropic is unable to pay rent on time and defaults, Broadcom will compensate the difference as agreed: 72.5% of the remaining lease amount minus the proceeds from selling the equipment. For instance, if the remaining amount is $100 and the equipment sells for only $60, Broadcom would need to pay $12.50.
D.A. Davidson's technology research head, Gil Luria, told Fortune that Broadcom had to reach such agreements, or competitors like NVIDIA would take the orders away, as NVIDIA also provides financing guarantees to top chip procurement customers. Luria stated, “To avoid falling behind in the competition where NVIDIA supports its customers, large semiconductor companies like Broadcom and AMD must keep up and support the buyers.” He upgraded Broadcom's rating to “buy” on October 27.
After a debt default occurs, whether investors can recover their funds largely depends on whether these chips can be subleased to other customers. Andrew Judich of credit rating agency KBRA compared NVIDIA GPUs with Google’s proprietary AI chips, TPUs produced by Broadcom, and told Fortune, “Custom TPUs are designed for a more specialized ecosystem, and the potential user base is more limited, making the sublease risk higher compared to NVIDIA GPUs.”
Judich noted that Broadcom's residual value backstop agreement can help investors recover funds when the proceeds from selling or subleasing equipment fall short of expectations, “but essentially this shifts part of the risk to the guarantor.” Therefore, when evaluating this financing, it is essential to examine the credit status of the guaranteeing companies, the legal effectiveness of the agreement’s terms, and the scope of compensation coverage.
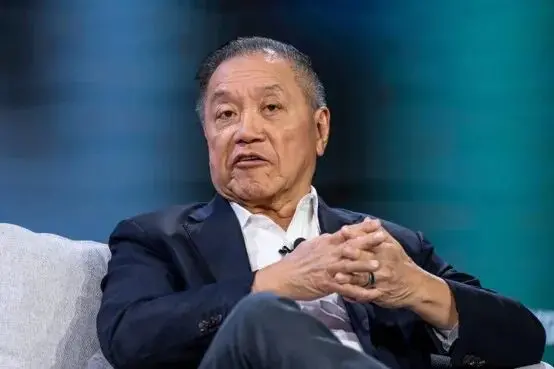
Broadcom CEO Hock Tan. Broadcom has agreed to provide guarantees to Anthropic in a financing agreement aimed at supporting the AI company's purchase of Broadcom's AI chips, TPUs. Image Source: David Paul Morris—Bloomberg via Getty Images
Stein van Nuwenhove, a professor of real estate and finance at Columbia Business School, believes that hardware manufacturers with diversified businesses, abundant cash flows, and not solely relying on AI business have the ability to absorb losses. However, if AI market demand cools, it will not only trigger guarantee compensations but also impact the hardware sales, cloud revenue, and investment valuations of the aforementioned partners. “Independent contracts will cause the impact of the same potential demand shock to flow into the balance sheets of multiple companies. A single loan might seem safe, but the concentration of risk in the entire system is rising and is harder to evaluate.”
Anthropic warns in its prospectus that the sustainability of its computing power expansion may heavily depend on whether a few cloud service providers, partners, and investors are willing and able to provide support. Among them, the two core partners, Amazon and Google, have already exceeded their operating cash flows in capital expenditures in the AI field. Over the past 12 months, Amazon reported a negative free cash flow of $42.4 billion, primarily due to increased investments in AI equipment; Google’s parent company Alphabet had a negative free cash flow of $9.1 billion in the third quarter. Although both companies still boast strong generating capabilities and smooth financing channels, ongoing support for Anthropic will compete for funds with their own AI infrastructure projects.
Dario Amodei once described a scenario where the growth rate of an AI company could be very rapid, but the scale of computing power procurement still exceeds its own capacity. In a podcast interview in February this year, he illustrated the financial pitfalls with an extreme hypothesis: a company procures computing power based on an expectation of 10-fold growth in revenue annually; but if actual revenue grows only 5-fold, it may struggle to settle its payments. Even if the future market space is enormous, the growth rate may lag behind the procurement arrangements made based on previous growth expectations. “If the forecast is off by two or three years, it could be enough to drag the company down,” he stated.
Complex Financing Conditions
According to an agreement reached in March 2026, Anthropic can issue up to $42 billion in convertible notes to Broadcom to pay for qualified quarterly rents, thus preserving cash. The interest will be added to the debt principal, and noteholders can convert the notes into Anthropic equity at a discount.
Under normal circumstances, these convertible notes have an annual interest rate of 9%, with interest included in the principal, and a conversion price of 90% of the market price. If agreed revenue targets are not met, the interest rate directly rises to 13%, and the conversion price is lowered to 85% of the market price, allowing the same notes to convert into more shares, further diluting existing shareholder equity. If performance thresholds are not reached for an extended period, Anthropic will lose its eligibility for future financing. Anthropic stated that the revenue threshold set by the agreement is far below recent actual growth rates: the company reported a 45% quarter-over-quarter revenue growth and over 1000% year-over-year growth in the third quarter.
Google and AMD also connect financial support to hardware delivery: when Anthropic signs a TPU lease agreement, some funds from Google can be activated; AMD’s investment payments are made after GPU delivery and deployment milestones are met.
Van Nuwenhove told Fortune, “Equity investments tied to hardware make Amazon and AMD bear risks but do not make them fully accountable as guarantors.” If Anthropic is unable to pay, Broadcom and Google will bear losses within the limits set by the backstop agreement, while risks exceeding that range will be borne by lenders.
Anthropic states that the company has continuously optimized its Claude large model over the years to make it compatible with chips from Amazon, Google, NVIDIA, and AMD, allowing for flexible allocation of computing power based on cost and performance. However, funding tied to a single supplier's equipment cannot be automatically transferred to other manufacturers. This could reduce Anthropic's flexibility when choosing chips for different workloads.
Can IPO fundraising yield greater flexibility?
As of September 30, Anthropic holds $146.6 billion in liquid funds, covering cash, short-term investments, and available bank credit, sufficient to cover current payments and expansion expenses; however, if bank credit is utilized, the company’s debt size will also increase.
Market analyst Tichnaka believes that abundant liquidity is favorable for bondholders, but whether Anthropic’s debt can achieve an investment-grade rating “depends on how rating agencies evaluate its enormous future commitment expenditures, short operating history, and intertwined business relationships.”
He stated, “The company has now disclosed future performance commitments of $895 billion, higher than our initial estimate of about $600 billion.” The massive spending commitments and complex partnership networks will limit the company’s ability to secure low-cost financing at investment-grade spreads (the lower premium relative to benchmark rates typically paid by investment-grade borrowers).
“The core issue is whether the compounding growth of revenue can outpace computing costs and cover future performance expenditures.” He continues to monitor two signals: whether Anthropic will further increase future performance commitments and how its liquidity situation evolves. “Utilizing revolving credit is also a potential warning signal,” he added.
Anthropic has launched its own cloud computing infrastructure project, Anthropic Direct, separating data center site leasing from large-scale chip procurement, allowing time to gauge market demand before locking in equipment orders. The company can first secure third-party operated dedicated infrastructure and finalize chip orders later. The prospectus shows the preparation period for data centers is longer than that for deploying internal hardware. Once the self-built dedicated infrastructure is officially put into production, the company will be able to use low-cost long-term computing power to replace expensive short-term leasing resources.
In the AI data center demonstration project modeled in Van Nuwenhove's paper, computing power devices and related systems account for about two-thirds of the initial investment, with the remaining portion for data center buildings and power supplies.
Even if Anthropic first leases the data center and delays chip procurement, it still needs to pay for the idle data centers. Van Nuwenhove pointed out that even if the power supply for the data centers has been secured, “if the final data center demand does not meet expectations, the data center will become stranded assets” (fixed assets that lose economic value prematurely due to technological advancements, changes in market demand, or policy adjustments, making it impossible to recover investment costs), meaning its business revenue cannot cover its investment costs, and it will be difficult to find a buyer.
Anthropic states that to reduce dependence on partners for funding infrastructure and equipment, it partly depends on whether it can secure financing from independent channels based on its own credit. Funds from shareholders introduced through the IPO can be directly used for computing power procurement, without waiting for specific supplier hardware to reach delivery or deployment stages. Moreover, the Anthropic Direct plan allows for delayed equipment procurement, enabling self-raised funds to reduce Anthropic's reliance on financing support from equipment suppliers when comparing hardware and financing options.
IPO fundraising will greatly enhance Anthropic's initiative in hardware selection and financing negotiations. But as Van Nuwenhove stated, “Supplier financing can support the implementation of infrastructure, but in the end, repaying debt still relies on revenue generated from end customers.” (Fortune Chinese Network)
·Anthropic's latest IPO prospectus shows that its cumulative data center expenditure commitments may reach $895.4 billion by 2045, highly relying on a complex vendor financing backstop mechanism, reflecting the extremely high financial leverage and risks behind the AI arms race, alerting the market to the potential systemic crises underlying aggressive expansion.
·To cope with competition, chip suppliers like Broadcom have transferred some market risks onto their balance sheets through equipment financing guarantees, revealing the hidden worries beneath the surface prosperity of the AI supply chain: once demand fails to meet expectations, the intertwined network of guarantees can easily trigger a chain reaction.
·Amazon and Google face pressure on free cash flow due to AI infrastructure, and their continued funding for Anthropic will compete for capital with their own projects, highlighting a pain point faced by the tech giants: as their generating capacity conflicts with AI capital expenditures intensifies, whether revenue compound growth can outpace massive computing costs will determine the sustainability of future commercialization.
Fortune Chinese Network has made deletions and adjustments to the original text.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


