Written by: Rita
In the Micron Technology 4Q outlook report released on September 11, 2026, Goldman Sachs maintained a neutral rating with a 12-month target price of $1100. Based on the closing price of $977.41 on September 10, there is an upside potential of 12.5%. The target price is based on a normalized earnings per share of $62 at 18 times. Goldman Sachs predicts that Micron’s revenue this quarter will be $51.9 billion, with a gross margin of 87.3% and earnings per share of $32.54, all exceeding market consensus.
Goldman Sachs analyst James Schneider noted in the report that investors are focused on strategic customer agreements (SCA), capital return plans, and the trends of HBM4 products. With DRAM and NAND supply remaining tight, Goldman Sachs expects Micron to produce another strong quarter, with revenue and guidance likely surpassing market expectations. Investor positioning is slightly positive due to ongoing tightness in DRAM and NAND, although some investors are concerned about the long-term supply increases from competitors, especially in China.
Estimated Revenue of $51.9 Billion Exceeds Consensus
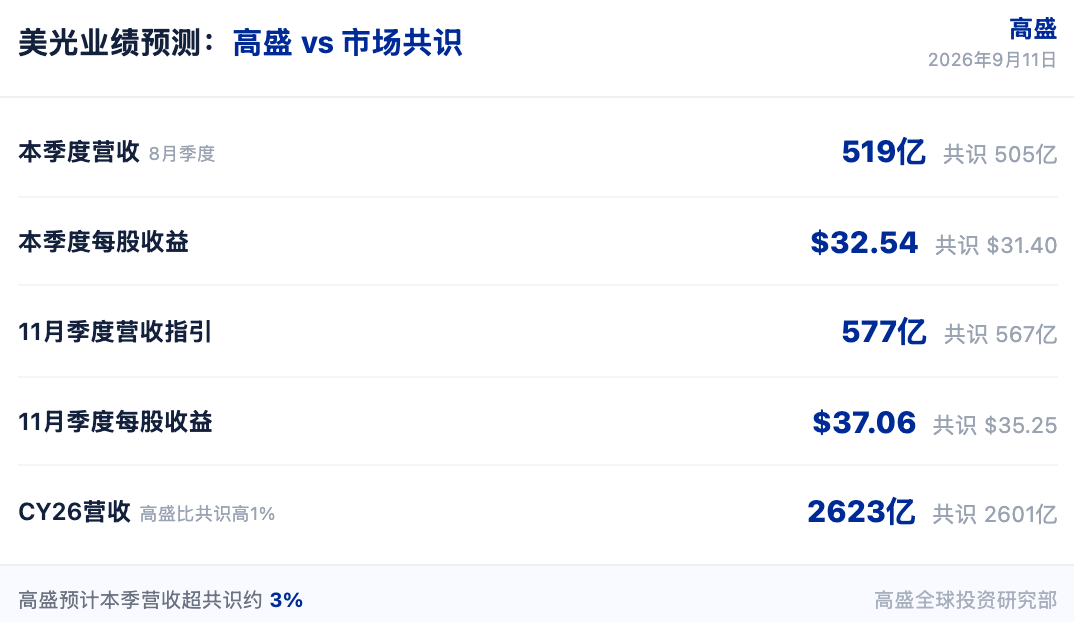
Goldman Sachs estimates that Micron's revenue this quarter will be $51.9 billion, while market consensus is $50.5 billion. The expected gross margin is 87.3%, compared to the market consensus of 87.0%. Earnings per share are expected to be $32.54, above the market consensus of $31.40. Revenue is expected to exceed consensus by about 3%.
For the guidance for November quarter, Goldman Sachs estimates revenue of $57.7 billion, while market consensus is $56.7 billion. The gross margin is expected to be 88.1%, compared to the market consensus of 87.5%. Earnings per share are predicted to be $37.06, above the market consensus of $35.25. Goldman Sachs expects Micron to guide for low double-digit growth in revenue for the November quarter, driven by product mix and incremental pricing.
Goldman Sachs believes that the price momentum in DRAM continues, with investor expectations being somewhat high but more moderate compared to previous quarters. Micron currently holds about a 20% share in HBM, and investors expect the company to maintain or expand this share.
CY26 Revenue and EPS Above Market
Goldman Sachs’ revenue and earnings per share forecasts for CY26 are 1% and 3% higher than market consensus, respectively. The estimated revenue for CY26 is $262.3 billion, compared to market consensus of $260.1 billion. Revenue for CY27 is estimated at $267.6 billion, with consensus at $264.7 billion. Revenue for CY28 is expected to be $280.2 billion, while consensus is $260.6 billion.
Goldman Sachs also introduces its projection for CY29, estimating revenue of $284.5 billion and earnings per share of $174.22. Goldman Sachs has raised its revenue and earnings per share forecasts based on the latest outlook for DRAM demand and recent pricing trends. The revenue forecast for CY27 is 4.9% higher than previous estimates, and the gross margin forecast is 80 basis points higher than older predictions.
Strategic Customer Agreements and Capital Returns are Key Focuses
Goldman Sachs believes investors expect Micron to sign more strategic customer agreements and are focusing on the pricing levels compared to previous agreements. The pricing structure of these strategic customer agreements is a market focus, which directly affects revenue visibility and profit margins for the upcoming quarters.
Regarding capital returns, Goldman Sachs expects comments on stock buyback plans to be a key point of market interest, especially following the lifting of restrictions from the CHIPS Act. Micron has previously faced limitations on buybacks due to the CHIPS Act. Following the lifting of these restrictions, the market is focused on whether the company will initiate a large-scale buyback. Goldman Sachs believes that the scale and timing of capital return plans are key variables affecting the stock price.
HBM4 Roadmap Determines Share
Regarding the HBM roadmap, Goldman Sachs expects Micron to comment on its HBM market share and provide more information on HBM4 shipments and HBM4E sampling. Goldman Sachs believes investors expect Micron to maintain or expand its current approximately 20% HBM share. The shipment pace of HBM4 and the progress of HBM4E sampling are core indicators for assessing Micron's position in the next-generation high bandwidth memory competition.
Goldman Sachs identifies upward risks including continued execution of the HBM roadmap and share growth, with a substantial increase in the HBM content of AI accelerators. Downward risks include CXMT continuing to gain DRAM market share, negatively impacting pricing dynamics. CXMT is a Chinese DRAM manufacturer, and its share expansion may suppress DRAM prices.
Goldman Sachs pointed out that after the earnings report is released, stock discussions will continue to focus on long-term customer agreements and excess capital returns, as well as the long-term supply increases, especially in China. Goldman Sachs believes the ongoing debate in the market regarding Micron is about how long the current pricing advantages due to tight supply can last and whether the production capacity expansion of Chinese competitors will change the supply and demand dynamics.
Disclaimer
This article is a summary and interpretation by Chao Xiang Research of a third-party brokerage research report (Goldman Sachs, September 11, 2026), combined with publicly available market information. The ratings, target prices, earnings forecasts, and related judgments quoted in this article are the views of the analysts from the brokerage and represent the stance of their institution only, not the views of Chao Xiang Research, nor does it constitute any investment advice.
The market carries risks, and decisions should be made independently. This article should not be used as a basis for buying or selling any securities.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


