MEV sandwich attacks are not order flow payments but front-running prohibited in regulated markets.
Written by: Yuval Rooz, Co-founder and CEO of Digital Asset
Translated by: AididiaoJP, Foresight News
Note: The author is the co-founder and CEO of Digital Asset, which developed the Canton Network.
MEV priority fees are merely a lower bound on losses; front-running is the hidden bill
Describing MEV as "the cryptocurrency version of order flow payments" is a common saying in the industry. The author believes this analogy is flawed.
Order flow payments come with best execution, price protection, and disclosure requirements, whereas MEV sandwich attacks do not. Retail investors pay worse execution prices on public chains, which are not visible and not itemized.
The article has three core judgments.
First, order flow payments come with protections, while MEV does not. Second, MEV priority fees underestimate harm. The front-runner only pays the validator a portion of what it takes from the trader. Third, MEV is a design choice, not a natural law. Sandwich attacks require two prerequisites: visibility of pending orders and the ability to pay to insert ahead of them. Both prerequisites can be removed.
The author also reminds us that meme coins are the most obvious scenario of harm currently, and tokenized stocks are next.
1. The "market integrity" that was skipped
A recent guideline tells financial institutions: permissionless chains meet financial integrity standards. However, this guideline discusses anti-money laundering and sanctions compliance, without addressing market integrity.
"Permissionless Networks and Financial Integrity" was authored by Rebecca Rettig (COO and Chief Legal Officer of Jito Labs), Omid Malekan (Columbia Business School), and Michael Mosier (former Acting Director of FinCEN). The full text is 27 pages long, and does not mention MEV, front-running, or sandwich attacks even once.
The paper itself circumscribes this issue. Footnote 6 lists "transaction ordering certainty" as outside the scope of discussion, claiming that existing work has "substantially alleviated" it, but does not provide evidence. Transaction ordering is precisely where retail investors lose money.
The paper's own statements expose the issues it skips over.
It does not accurately describe the fees. The paper states that users pay protocol-specified fees to "validator chosen by the protocol." However, on Solana, users and bots also pay external priority fees to control where transactions land. This market is operated by Jito, which is the company of the first author.
It lists rent extraction as a risk. The paper states that institutions can avoid risks like "network operator rent extraction" on permissionless networks. MEV is precisely rent extraction conducted by network operators.
It promises confidentiality to competitors. The paper says that institutions can "give no information to competitors" when trading. But on a chain where pending orders can be seen and front-run, institutions essentially disclose their next moves to competitors.
After reading this guideline, institutions may think that integrity issues have been solved. However, the issue of clients' execution prices has not been addressed at all.
2. Why MEV cannot be likened to order flow payments
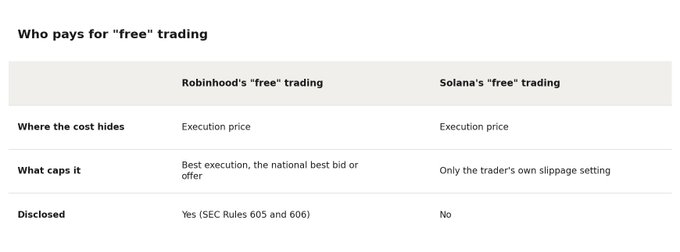
A common defense is that MEV is just the crypto version of order flow payments. In traditional finance, market makers also profit from retail orders, which is why Robinhood trades for free.
This comparison overlooks all the protections that make order flow payments still viable.
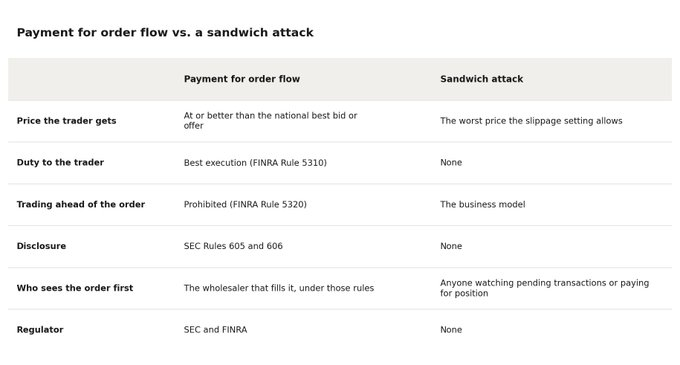
Order flow payments require brokers to still achieve best execution, with transaction prices meeting or exceeding the national best bid and offer, and disclose relevant arrangements. Traders subjected to sandwich attacks do not receive any of these protections.
Even with these protections, order flow payments remain controversial. In 2014, UK regulators required brokers to stop accepting order flow payments (FCA TR14/13). In 2021, the European Securities and Markets Authority (ESMA) also stated that it is unlikely to comply with EU rules.
Using order flow payments to defend MEV is equivalent to borrowing the legality of a regulated practice while refusing to accept the rules that confer its legitimacy.
Not all MEV is equally harmful. Cross-market arbitrage can help prices converge, and liquidation can maintain solvency in lending markets, similar to high-frequency trading in traditional markets: racing to close price gaps and competing with colocated servers for early transactions.
However, competition in traditional high-frequency trading is fierce. Colocation is a publicly available service; any company can rent racks at data centers at published prices. Exchanges also ensure that every cable from colocated servers to the matching engine is of equal length, making racks at the far end of the hall as fast as those next door. Physical location is deliberately rendered irrelevant. Many companies race for the same opportunities from the same starting line, and the profit from a single price gap can be driven close to the cost of capturing it by competition.
Arbitrage MEV does not work this way in practice. Whoever controls ordering decides the winner, and there are very few winners.
On Ethereum, as of 24 hours till November 10, 2026, a single builder, Titan, built 53% of blocks through MEV-Boost, with the top three builders together making up 85% (relayscan.io). Theoretically, this is benign MEV; in practice, it is neither as competitive nor as open as the markets it is compared to.
The industry often claims public chains are fair because they are decentralized. The ordering layer speaks to another issue: thousands of validators, but ultimately a handful of companies decide the order of transactions. This is "decentralized performance."
Traditional markets are often described as closed systems, yet they achieve equal access by ensuring that cable lengths are uniform. Chains promising openness instead concentrate the most critical advantage.
Even if ordering rules are intended to protect liquidity, once positions can be bought, the rules also become ineffective. Hyperliquid gives cancellation priority, allowing market makers to cancel stale quotes before they are filled. However, a trading firm analyzing its data found that under heavy load, cancellations can be pushed to later blocks, whereas immediate or cancel orders, especially orders paying 8 basis points in priority fees, are hardly affected. When there are more than 40,000 transactions per second, 31% of failed cancellations are signed before they eat their paying orders. On November 9, 2026, $1.27 million of AVAX sell orders were eaten, causing market makers to lose about $13,000 in 10 seconds (analysis on X). Market makers whose quotes are swept away will widen spreads, and all traders will pay for it.
Sandwich attacks differ not in degree but in nature. The industry knows this. Jito shut down public memory pools to curb sandwich attacks, which itself acknowledges that this practice harms the users it is supposed to serve.
3. Priority fees are merely a lower bound on losses
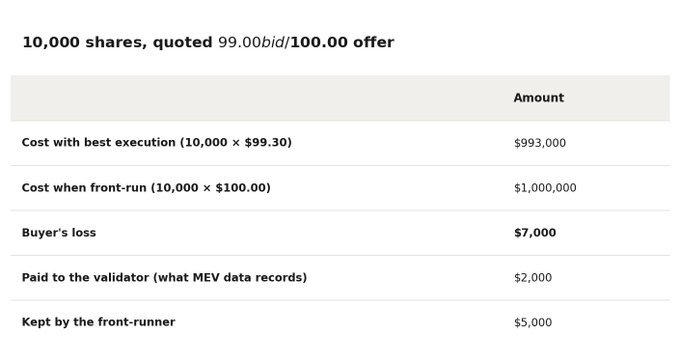
The money that front-runners pay to validators is always less than what they take from traders. No one will pay $8,000 for a trade that earns $7,000. Therefore, MEV priority fee data measures the minimum harm, not the total harm.
For example. A stock quotes $99 to buy and $100 to sell. A buyer places a limit order for 10,000 shares at $100. The market has enough liquidity to fulfill the entire order at $99.30, which is within the quoted range. Best execution requires the broker to find this. A front-runner sees the order first, buys the liquidity at $99.30, and then sells it to the buyer at the limit price of $100.
On-chain records show $2,000 MEV. The actual loss to the buyer is $7,000.
Real data also shows the same gap. From December 7, 2024, to January 5, 2025, a Solana sandwich program executed 1.55 million sandwich trades, earning 65,880 SOL, approximately $13.43 million in profit, while paying 22,760 SOL, about $4.63 million in Jito priority fees (Helius). Looking only at priority fees, one can see only about a quarter of the value taken from traders. Helius also points out this limitation: Jito data "does not include the profits of the seekers."
The same applies to retail scenarios. A meme coin buyer spends $1,000 with a slippage set at 10%. A bot jumps in front, pushes the price to the tolerance edge, and then sells afterward. The tokens the buyer receives are about $100 less than without the attack. If the bot pays a $30 priority fee to get into position, the data only shows $30; the trader's loss is $100. (Example figures.)
There are two calibrations to adhere to. The total priority fee includes benign MEV such as arbitrage, so when discussing lower limits, sandwich-specific priority fees should be used. The trader's loss equals the priority fee plus bot profits; these cannot be added again, lest there be double counting of sandwich losses.
4. Data from Solana: large scale, concentrated in meme coins, and still ongoing
Sandwich attacks on Solana are large in scale, concentrated in meme coins, and have not stopped.
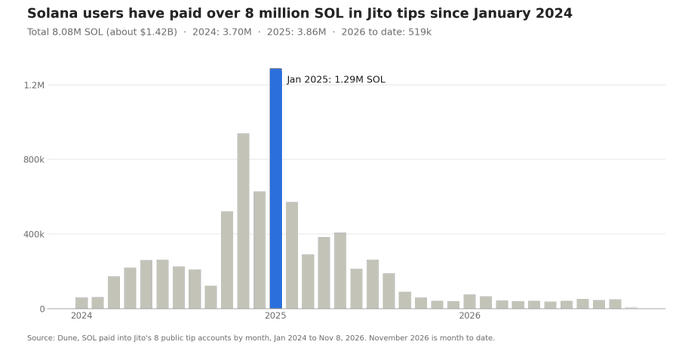
From January 2024 to November 8, 2026, Jito priority fees totaled 8.08 million SOL, about $1.42 billion (Dune query on 8 public priority fee accounts of Jito).
The Solana staking share running the Jito validator client increased from 48% at the start of 2024 to 92% at the start of 2025 (Helius).
A sandwich program executed 1.55 million sandwiches in the 30 days up to January 5, 2025, with a profit of $13.43 million and a priority fee of $4.63 million (Helius).
Among the 20 tokens most attacked, 16 were created on pump.fun (Helius).
In a recent reporting window, 606 attackers launched 224,964 sandwiches, impacting 52,728 victims, with data accessed on November 7, 2026 (sandwiched.me).
Priority fees peaked at 1.29 million SOL in January 2025 during the meme coin frenzy, then dropped back to about 40,000 to 50,000 SOL per month. The total amount of 3.7 million SOL in 2024 differs by less than 2% from Helius's reported 3.75 million SOL. The priority fee is the lower limit of trader losses, not the total amount.
The core figure is: since January 2024, Solana users have paid about $1.42 billion for trading positions. Of this, $661 million in 2024, $705 million in 2025, and $49 million in 2026 so far; $285 million just in January 2025. The dollar values are converted using Dune's average SOL prices for each month.
Not every priority fee is used for sandwiches. Priority fees also buy fast packing and fund arbitrage. But the proportion of sandwiches is itself a lower limit since bots take away most of the profits. In the aforementioned Helius case, the priority fee accounted for about a quarter of the extracted value.
5. Validator economics: who pays for "free trading"
On large chains, ordering revenue has become the core of validator income.
On Solana, users and bots paid 3.75 million SOL in Jito priority fees in 2024; the share of validators running the Jito client rose from 48% to 92% (Helius). Estimates suggest that Solana has an annual revenue of around $1.5 billion, of which only about $100 million comes from base fees (RYT, March 2026). Base fees are close to zero, with money primarily coming from positions.
This raises an incentive issue. As validator income rises with ordering competition, those protecting the network earn more when users' execution prices worsen. There is no need for anyone to act maliciously; the income structure itself is thus.
Removing MEV would significantly change validator economics. Revenue would have to come from elsewhere:
- More token issuance. Validators take newly minted tokens, diluting all holders.
- Higher explicit fees. Users pay visible fees, and "free trading" is no longer free.
- Fewer validators. Operators unable to cover costs will exit, weakening decentralization.
- Another model. Proposals such as burning MEV, auctioning order flow, and returning proceeds to users attempt to recapture value. The Canton Network rewards validators for operating the network rather than rewarding them for ordering user transactions.
The uncomfortable conclusion is that public chains appear cheap partly because users pay through execution prices rather than visible fees. This is similar to the criticism aimed at zero-commission brokers, except that broker clients still have best execution and disclosure protections.
6. Removing the two prerequisites
Sandwich attacks require two things: attackers must see pending orders and be able to pay to insert themselves ahead. Removing one makes the attack harder; removing both makes it impossible.
Jito has closed public memory pools, partially removing the first condition. Initially, it reduced harmful MEV, but private memory pools emerged, and Jito's own analysis found that more and more sandwich attacks occur outside its auctions. Sandwich attacks continue today: a tracker recorded over 220,000 attacks and more than 52,000 victims in a recent reporting window. No good intentions can fix a design that profits from selling positions.
The author states that, as described, the Canton Network attempts to remove the two prerequisites for sandwich attacks:
- No public memory pools. Pending transactions do not enter a publicly visible queue, making it difficult to observe pending orders.
- No paid ordering market. Users cannot pay priority fees or tips to get validators to change transaction landing spots.
If these two points hold, front-runners see neither orders nor buy positions ahead, thus sandwich attacks lack the conditions for implementation within this network design. This refers to mechanical conditions, not external validation of actual operational effects.
According to Canton Network documentation, transactions are ordered by Global Synchronizer, employing a Byzantine Fault Tolerance protocol run by independent Super Validators, ensuring no single entity controls ordering. The documentation also states that these operators cannot see transaction data but can only see limited metadata required for ordering and confirmation. Network fees are paid in Canton Coin and burned; validators earn newly minted Canton Coin for providing services rather than for priority fees paid by users racing for positions.
SupaNova is a meme coin trading application recently launched on the Canton Network, and the author uses it as an observational case. Meme coin trading is among the scenarios where other chains extract the most MEV from retail. According to the author, this kind of protection is determined by network-level mechanisms, not depending on how an individual application is built. However, this judgment is still based on the project parties' documentation and the author's stance, and cannot replace independent assessment.
7. Questions issuers should answer
Meme coins are speculative corners, and some will say traders accept risks. However, the same infrastructure now begins to carry stocks.
xStocks offers over 100 tokenized U.S. stocks and ETFs, reporting over $47 billion in trading volume, and trades on Solana venues like Jupiter (xStocks). Ondo Stocks offers over 470 tokenized stocks and ETFs on Ethereum, BNB Chain, and Solana (Ondo). bStocks and Robinhood's stock tokens for international customers also extend the same model.
When the assets are tokenized stocks, sandwich attacks are no longer a gray area. Trading ahead of customer orders in securities trading is front-running, a practice prohibited in regulated markets for decades. A chain where validators are rewarded for ordering transactions has integrated this practice into its settlement layer.
The issuers' question is simple: will you list stocks on a venue that allows others to front-run every one of your shareholders' orders? When you tokenize on a chain with MEV, that is precisely the venue you choose.
This article's data comes from Solana because it is publicly available and the meme coin market is the largest. However, Solana is not an exception. Any chain where pending orders are visible and positions are for sale allows for sandwich attacks, and mainstream public chains share this design.
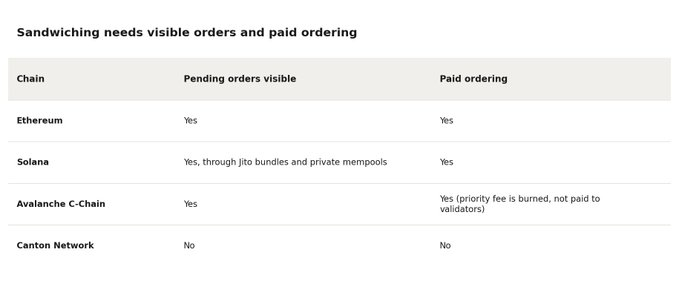
On Avalanche's C-Chain, the documentation states that transactions are prioritized first by priority fees, then by timestamps. Priority fees will be burned, and validators cannot directly earn income from them, but front-runners can still bid higher than the victim to compete for positions. Thus, while burning fees eliminates incentives for validators, it does not eliminate the attacks themselves.
The topic of this article stems from two aspects: first, SupaNova's launch on Canton Network, and second, the MEV problems exposed in meme coin trading. The influence of this problem is not limited to meme coins. As real-world assets are tokenized, supporters often describe tokenization as bringing faster settlement, broader access, and lower costs. If the infrastructure carrying these assets results in worse execution quality than currently, it is challenging for these expectations to hold. If on-chain finance offers 24/7 markets and instant settlement but extracts corresponding benefits from each transaction, the outcome undermines the value proposition of on-chain finance. MEV is not immutable; it is a design choice. Chains without memory pools and that do not offer paid ordering choose different mechanisms.
References
- Rettig, Malekan and Mosier, The Compatibility of Permissionless Networks and Financial Integrity: A Practical Guide for Financial Institutions, SSRN abstract 7343938 (2026)
- RYT, "The Architecture Nobody's Building" (March 30, 2026)
- Canton Network, FAQ
- Canton Network, The Global Synchronizer
- FCA, TR14/13: Best execution and payment for order flow (2014)
- ESMA, warning on payment for order flow (2021)
- xStocks
- Ondo Stocks
- Helius, "Solana MEV Report"
- sandwiched.me, Solana sandwich tracker
- Avalanche Builder Hub, "Transaction Fees"
- relayscan.io, MEV-Boost builder statistics
- Analysis of Hyperliquid cancel priority under load, X (November 2026)
- FINRA Rule 5310 (Best Execution); FINRA Rule 5320 (Prohibition Against Trading Ahead of Customer Orders); SEC Rules 605 and 606 of Regulation NMS
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


