Article | Li Hailun
Editor | Su Yang
In the future, the familiar scene of "Lord Huang" taking the stage at the NVIDIA GTC conference and waving to the audience may no longer be seen.
On November 12, local time in the United States, Jensen Huang announced his departure from NVIDIA, where he had been in charge for 33 years. NVIDIA's stock price plummeted about 14% in intraday trading, then narrowed its losses, ultimately closing down about 4.3%.
Andreessen Horowitz general partner Martin Casado referred to it as "a dark day."
Since founding NVIDIA in 1993, Jensen Huang has virtually dominated every major transformation of the company. From the early graphics processing chips to the CUDA computing ecosystem, and now to the AI data center business, NVIDIA’s ability to seize several rounds of technological change is closely related to Huang’s judgments and long-term investments in technology direction.
Especially in this wave of generative AI, Huang not only drove NVIDIA's transformation from a chip supplier to an AI infrastructure platform but also was deeply involved in product roadmap development, supply chain coordination, and cooperation with major clients.
NVIDIA's current market position is largely built on this business strategy.
For NVIDIA, Huang's departure does not mean an immediate impact on existing businesses. After years of development, the company has established mature technical teams, product roadmaps, and supply chain systems, and these advantages will not vanish with the departure of a single manager.
However, after losing Huang as a core decision-maker, can NVIDIA continue its rapid growth of the past few years? What new challenges will this company, which is at the core of the global AI industry, face next?
01 Successor Does Not Equal Helmsman
The current interim CEO of NVIDIA, Colette Kress, has served as CFO for over 13 years and participated in the entire process of NVIDIA's transformation from a gaming graphics card company to an AI infrastructure giant. She is familiar with the company's financial situation, client contracts, supplier arrangements, and capital expenditures.
She has also long appeared in earnings call meetings alongside Huang and is a familiar figure to Wall Street.
KeyBanc Capital Markets analyst John Vinh believes Kress' appointment as interim CEO is a positive sign because of her long tenure and deep understanding of NVIDIA's business and strategy. eToro chief analyst Josh Gilbert also views Kress as a clear choice for stabilizing the company. She is familiar with the business and can represent the company when the market needs management to provide certainty.
However, this does not mean Kress can immediately take over Huang's original decision-making responsibilities. According to The Information, the interim CEO is not the main driver of significant company decisions and is not responsible for setting the major decision agenda. An interim CEO and a long-term helmsman are two different matters.
Previously, The Information cited insiders stating that Kress is not the primary promoter of NVIDIA's major decision agenda; in some high-risk deals, she tends to control risks, as seen with the OpenAI credit support arrangement.
Huang had pushed NVIDIA to provide large-scale credit support for OpenAI, with initial discussions reaching $250 billion to support its data center construction. Kress took a cautious approach. Consequently, the arrangement was broken down, with NVIDIA's supported first part being around $100 billion.
Bernstein analyst Stacy Rasgon believes Kress' appointment will help stabilize short-term business, and he does not worry that this management change will immediately affect NVIDIA's operations. However, he is more cautious about long-term issues: whether the new CEO can take over Huang's control over the product roadmap, as well as his network of relationships with clients, suppliers, employees, and the entire industry ecosystem, remains highly uncertain. Rasgon subsequently downgraded NVIDIA's stock rating and target price.
Goldman Sachs analyst James Schneider also pointed out that NVIDIA does not lack a mature functional management team, as there are experienced leaders in chip design, software, systems, and finance, but Huang's technical vision, industry influence, and cross-enterprise coordination abilities are difficult for an ordinary professional manager to directly replace.
Currently, among internal candidates, the most notable is NVIDIA's senior technology executive Ian Buck. He joined the company in 2004 and has long been involved in GPU general computing and CUDA ecosystem development, currently responsible for AI hardware and software products aimed at large-scale cloud vendors.
Among external candidates, Arm CEO Rene Haas has been mentioned by multiple analysts. He previously led the computing products business at NVIDIA, joined Arm in 2013, and later became CEO. Additionally, Apple Executive Chairman Tim Cook, Apple hardware head Johny Srouji, and Palo Alto Networks CEO Nikesh Arora have also been named.
Investor Armina Rosenberg suggested a possibility: NVIDIA could consider having Kress handle operations and finance, while Buck manages products and technology, creating a management arrangement similar to co-CEOs.
After all, over 60 executives that Huang directly managed is a significant number, and NVIDIA's decision-making system has long operated around him.
02 Can CUDA Be Preserved?
Looking back at NVIDIA's development history, one of Huang's most important roles has been to drive the company's continuous investment in technological directions that have not yet formed clear commercial returns.
The most representative case of this is CUDA.
In 2006, NVIDIA launched CUDA, allowing GPUs to handle general computing tasks beyond graphics rendering. In 2012, AlexNet, trained using NVIDIA GPUs, made a breakthrough in the ImageNet competition, making GPUs an important computing platform for deep learning. Since then, NVIDIA has continued to improve the CUDA toolchain and computing libraries, and developers have gradually built model training, optimization, and deployment processes around this system.
This is also the reason why competitors find it difficult to chase NVIDIA solely based on chip performance. Even if companies procure GPUs or dedicated chips from other manufacturers, they need to re-adapt existing code, models, and software tools. For clients that have already invested heavily in using CUDA, migration is not simply a hardware change.
However, the methods of AI computation are changing, and CUDA must expand accordingly. In recent years, NVIDIA's advantages have mainly been reflected in large model training; as the industry shifts towards large-scale inference, clients are beginning to pay more attention to the computational cost per token, GPU utilization, and response speed. NVIDIA plans to launch Dynamo 1.0 in 2026, specifically for resource scheduling and request management in large-scale AI inference, trying to extend the competition from GPU performance to the entire inference system. It is also integrated with software like TensorRT-LLM and supports mainstream open-source inference frameworks.
AI agents and robots open up new application spaces. Agents need to continuously call models, data, and external tools, while robots need to handle vision, spatial understanding, and real-time control. NVIDIA is extending its underlying computing capabilities to these scenarios through CUDA-X, Isaac robot platform, Omniverse simulation environment, and Cosmos models. In the future, the use of CUDA may no longer be limited to data centers but will also enter factories, vehicles, and robotic equipment.
However, this software barrier is not unshakeable. Currently, AMD is improving its ROCm ecosystem, while Google TPU and Amazon Trainium are also developing their software systems. Open-source tools like PyTorch and Triton are reducing developers' reliance on specific hardware platforms. If more models can be adapted to different chips through a unified framework, the migration costs associated with CUDA may gradually decrease.
This is exactly the long-term issue NVIDIA needs to face after Huang's departure. The success of CUDA comes from a long return cycle of technical investment, while inference, agents, and physical AI may be the entry points for the next round of ecological expansion. Who determines the priority of investment in these directions and who drives the software platform to continuously adapt to new computing methods will impact NVIDIA's ability to sustain the ecological advantages it has accumulated in the past.
03 How to Fulfill the $279 Billion Commitment?
After Huang's departure, another issue the market needs to pay attention to is the massive supply and capacity commitments NVIDIA has already made.
NVIDIA's quarterly report as of July 26, 2026, disclosed that the total amount of supply and capacity commitments reached $279 billion, an increase of approximately $160 billion from around $119 billion in the previous quarter.
According to the distribution of fulfillment timelines, there is approximately $92 billion remaining for fiscal year 2027, about $87 billion for fiscal year 2028, around $88 billion for fiscal year 2029, with approximately $12 billion allocated for later periods.
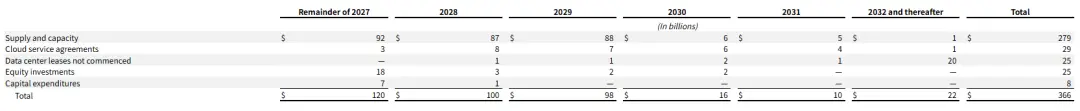
This $279 billion is not the customer orders that have already been received, nor is it the cash that NVIDIA has already paid. It mainly corresponds to the procurement and capacity arrangements made by the company to meet future demand with suppliers and capacity partners. NVIDIA needs to secure advanced processes, packaging, memory, and other key resources in advance to ensure that Blackwell and subsequent products are delivered as planned.
The issue here is that commitments on the supply side may not necessarily coincide with customer demand for fulfillment.
Large data centers require long cycles from financing, site selection, power supply, to construction and deployment. Even if clients have planned to procure GPUs, they may delay purchases due to power access delays, construction hindrances, insufficient financing, or changes in the deployment pace of next-generation products. NVIDIA also noted in its 10-Q filing that clients may delay or cancel purchases due to infrastructure, funding, and technology adoption progress.
If client demand is fulfilled at a slower pace than expected while NVIDIA has already secured upstream capacity, it could face inventory buildup, cancellation costs, and mismatches in supply and demand. Even if other buyers can eventually be found, generational changes in products can also affect pricing and gross margins.
Another easily confused figure is the approximately $36 billion AI cloud service agreement commitments disclosed by NVIDIA.
This kind of arrangement typically involves multi-year cloud service capacity collaborations and is not counted the same way as the $279 billion supply and capacity commitments. NVIDIA obtains cloud computing capacity through partners and may also resell some capacity to third parties; as capacity is utilized, related commitments will similarly decrease. However, if external customer demand is insufficient, NVIDIA may still bear certain procurement responsibilities.
These arrangements reflect a change in NVIDIA's business model: the company is no longer only procuring chips based on orders and delivering products but is increasingly involved in the resource allocation of the entire AI infrastructure in advance. Huang was adept at driving project implementation through client relationships and industry influence; his successor will need to balance maintaining growth and controlling financial risks.
04 The Next Engine of Growth?
In recent years, NVIDIA has seized the wave of generative AI and become a major beneficiary of global AI infrastructure construction. However, for this company, whose quarterly revenue is already approaching $100 billion, how to maintain rapid growth is becoming increasingly important. NVIDIA's most important source of growth currently still lies in data centers. In the second quarter of fiscal year 2027, the company's revenue reached $96.221 billion, a year-on-year increase of 106%; data center revenue was about $89 billion, a year-on-year increase of 117%, accounting for the vast majority of total revenue. The company provided revenue guidance of $108 billion for the third quarter, indicating that growth momentum remains strong.
Additionally, as major global technology companies continue to expand AI infrastructure investments, the Blackwell platform is being deployed on a large scale, and the next-generation Vera Rubin platform has also begun production shipments.
Moreover, NVIDIA is looking for other new growth opportunities.
Among them, AI inference is an important direction. As large models transition from training to large-scale applications, businesses need continuous model calls to complete various tasks, and the popularity of AI agents may further increase computational demands.
Compared to model training, inference business places greater emphasis on computation costs, energy consumption, and operational efficiency. NVIDIA is working to improve inference performance through new generation chips and complete systems, aiming to continue expanding its business scale in this market.
Fields such as robotics, autonomous driving, and industrial AI are also seen by NVIDIA as future growth directions. For instance, as more countries and regions seek to build autonomous and controllable AI infrastructure, sovereign AI is bringing about new chip procurement demands. Robotics and autonomous driving are expected to further broaden the application range of GPUs and related computing platforms.
However, whether these new markets can reach the scale of current data center businesses still needs time to be validated.
Meanwhile, the competition NVIDIA faces is also changing.
In the past, NVIDIA mainly competed with chip manufacturers such as AMD. Now, large clients like Google, Amazon, and Microsoft are developing their own AI chips to lower computing costs and reduce dependence on a single supplier. Broadcom is also participating in large technology companies' chip research and development through customized ASIC business. These products may not completely replace NVIDIA GPUs in the short term, but they are already providing clients with more choices for certain computational tasks.
Jensen Huang led NVIDIA to seize the growth opportunities brought by generative AI. Next, in the constantly changing landscape of AI industry competition, who will determine NVIDIA’s next steps and whether they can lead the company to grasp the next round of growth opportunities will become a new test.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。